At-Fault Driver Has No Insurance or Is Underinsured?
Injured by an uninsured or underinsured driver? Learn what to do if the at-fault driver has no insurance or is underinsured. Call (855)-545-2917 for a free case review.
By Hannah Briggs
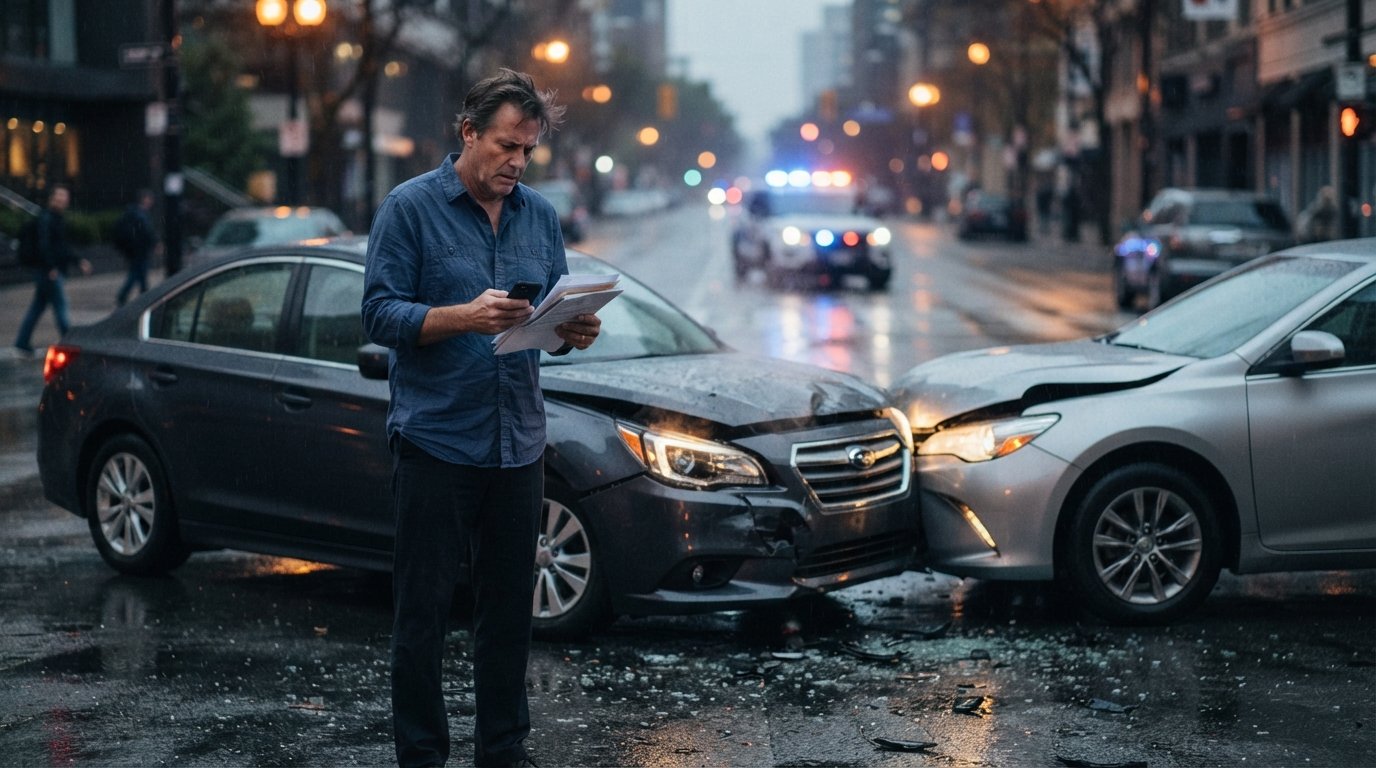
You hear the crash, feel the jolt, and exchange information at the scene. Weeks later, you learn the driver who hit you let their policy lapse, carried only the state minimum, or fled before you could get a plate number. Suddenly the question is not who caused the crash, it is who pays for it. The answer is more workable than most injured people expect, but only if you act in the right order and protect the evidence that supports your claim. This guide walks through what to do if the at-fault driver has no insurance or is underinsured, from the first phone call to your own carrier through the last negotiation with a claims adjuster.
Understand What Uninsured and Underinsured Actually Mean
An uninsured driver has no liability coverage in force at the time of the crash. That includes drivers who never bought a policy, drivers whose coverage lapsed for nonpayment, and hit-and-run drivers who are never identified. An underinsured driver does carry coverage, but the policy limit is too low to pay for the harm caused. Many states allow minimum limits as low as $25,000 per person, and a single emergency room visit, surgery, or week of lost wages can burn through that number quickly.
The distinction matters because each scenario routes your claim through a different set of rules. With an identified uninsured driver, you may still pursue that person personally, though collecting from someone with no assets is often impractical. With an underinsured driver, you first exhaust their policy, then turn to your own coverage for the gap. In both cases, your own auto policy, specifically the uninsured and underinsured motorist (UM/UIM) portions, usually becomes the most important contract in the room.
Fault rules also vary by state. Some states use pure comparative negligence, where your recovery is reduced by your share of fault. Others use modified comparative fault or contributory negligence, which can bar recovery entirely if you are found even slightly responsible. Because these rules, insurance requirements, and filing deadlines differ from state to state, the practical steps below should be adapted to your jurisdiction with guidance from a licensed attorney.
Steps to Take Right After the Crash
The first 48 hours set the foundation for everything that follows. Even if the other driver admits fault and promises to "take care of it," treat the scene as if a dispute is coming, because with an uninsured or underinsured driver it usually is. Your goal is to document everything a claims adjuster will later question.
- Call the police and request a written report. An official report creates a neutral record of the crash, the parties, and any citations issued.
- Photograph the damage, the positions of the vehicles, the road conditions, visible injuries, and any skid marks or debris.
- Collect names, phone numbers, addresses, license plate numbers, and insurance information from every driver and witness.
- Seek medical attention the same day, even if you feel fine. Adrenaline masks symptoms, and a gap in treatment is one of the first things an adjuster uses to argue your injuries are unrelated.
- Notify your own insurer promptly. Most policies require prompt notice, and delay can jeopardize your UM/UIM claim.
Notice to your own carrier is not an admission that you were at fault. It is a contractual obligation, and it preserves the coverage you paid for. When you call, ask specifically whether your policy includes uninsured motorist and underinsured motorist coverage, what the limits are, and whether you also have medical payments coverage or personal injury protection that can pay bills while the liability question is sorted out.
How Uninsured Motorist Coverage Works
Uninsured motorist coverage is a first-party benefit, meaning you file a claim with your own insurer much as you would against the other driver's policy. It typically pays for medical bills, lost wages, pain and suffering, and other damages the uninsured driver legally owes you but cannot pay. Many states require insurers to offer UM coverage, though policyholders can sometimes reject it in writing, so check your declarations page rather than assuming you have it.
Two features of UM claims surprise people. First, your insurer steps into the shoes of the at-fault driver and may raise defenses that driver would raise, including disputing fault or the severity of your injuries. Second, if your UM limits are modest, you may be able to stack coverage from multiple vehicles on the same policy, or in some states combine UM limits across policies in the household. Stacking rules are state-specific and fact-specific, which is one reason a consultation with a licensed attorney can change the value of your claim significantly.
A hit-and-run crash is treated as an uninsured motorist claim in most states, but insurers often impose extra conditions. You may be required to report the accident to police within a set number of hours or days, and to show that the other driver's identity cannot be determined through reasonable effort. Failing to file a timely police report is one of the most common reasons hit-and-run UM claims are denied.
How Underinsured Motorist Coverage Fills the Gap
Underinsured motorist coverage applies when the at-fault driver has insurance, but the limit is not enough to cover your damages. The process usually runs in two stages. First, you settle with the at-fault driver's insurer for the full policy limit. Then you present the remaining, uncompensated portion of your damages to your own UIM carrier.
Insurers frequently require written consent before you settle with the at-fault driver, because that settlement releases the other driver and can affect the insurer's subrogation rights. Settling without notifying your carrier can forfeit your UIM benefits entirely. Read your policy language carefully, and if you are unsure, have an attorney review it before you sign any release.
UIM claims also require proof that the other driver was underinsured, which generally means showing the policy limit was less than the total value of your damages. That is why thorough documentation of medical treatment, wage loss, and future care matters so much. A demand package that clearly totals your damages above the at-fault driver's limit makes the UIM claim straightforward rather than contentious.
When the At-Fault Driver Has No Insurance and No Assets
Some injured people assume that suing an uninsured driver is pointless. It is true that a judgment against someone with no income or property may be difficult to collect, but the analysis does not end there. The at-fault driver may have assets you cannot see, may receive an inheritance, or may be covered under someone else's policy, such as a parent, spouse, or employer. In many crashes, the legally responsible party is not only the driver.
Potential additional sources of compensation include:
- The owner of the vehicle, if different from the driver, under permissive use or negligent entrustment theories.
- The driver's employer, if the crash happened during the scope of employment.
- A rideshare or delivery company's commercial policy, if the driver was working at the time.
- Your own UM/UIM, medical payments, or personal injury protection coverage.
- Health insurance, which may pay bills now and seek reimbursement later from your settlement.
Each of these sources has its own notice requirements, deadlines, and coverage limits. Mapping them early prevents the common mistake of settling with one insurer for less than the claim is worth, only to discover that other coverage existed and is now off the table because a release was signed.
If you are dealing with a DUI-related crash, there may be additional avenues worth exploring, including dram shop claims against a bar or restaurant that served an obviously intoxicated driver. Our guide on SR22 insurance requirements after DUI explains how those convictions affect a driver's insurance obligations, which can be relevant when you are evaluating whether the at-fault driver had valid coverage at the time of the crash.
Deadlines and Notice Requirements You Cannot Miss
Every part of an uninsured or underinsured motorist claim has a clock attached to it. The statute of limitations for personal injury claims varies by state, often running from one to three years from the date of the crash, but UM/UIM claims may be governed by the same statute or by a shorter contractual deadline in your policy. Missing the deadline usually means losing the claim entirely, no matter how strong the evidence.
Notice provisions deserve equal attention. Insurers often require notice of a hit-and-run or UM claim within days, and some policies require that you request UIM benefits in writing before settling with the at-fault driver. Because these rules are buried in policy language and state statutes, the safest approach is to notify every potentially responsible insurer in writing as soon as you know a claim is possible, and to keep proof of every letter, email, and phone call.
If you are unsure how the deadlines apply to your situation, it is worth speaking with a licensed attorney before time runs short. AutoInjuryAccident.com is a consumer matching site, not a law firm or lawyer referral service, and it does not provide legal advice. It does, however, allow injured people to request a free, confidential case review from participating attorneys who advertise on the site, with no obligation to hire anyone. Submitting a form does not create an attorney-client relationship.
Common Mistakes That Reduce or Destroy Your Recovery
Most bad outcomes in these cases trace back to a handful of avoidable decisions. Adjusters are trained to spot them, and they price their offers accordingly. Avoiding them keeps your claim in a much stronger position.
- Giving a recorded statement to the other driver's insurer without preparation. These statements are used to lock in details and catch inconsistencies later.
- Signing a quick settlement or release before the full extent of your injuries is known. Once signed, the claim is over.
- Skipping medical treatment to avoid bills, which creates gaps that insurers characterize as evidence you were not hurt.
- Posting about the crash or your recovery on social media, where defense investigators look for contradictions.
- Failing to tell your own insurer about the crash, which can void UM/UIM coverage you paid for.
Each of these mistakes is fixable if caught early. If you have already given a statement or signed something, an attorney can often still assess your options, but the sooner you get guidance, the more room there is to maneuver.
It also helps to understand how the broader legal system handles disputes between clients and the professionals who represent them, since fee disputes and malpractice questions occasionally arise alongside injury claims. Resources such as AttorneyLawsuit.com legal information cover topics like client rights, fee disagreements, and attorney misconduct, which can be useful background if you ever need to evaluate whether your representation is being handled properly.
Do You Need a Lawyer for an Uninsured Motorist Claim?
You are not required to hire a lawyer to file a UM or UIM claim, and some smaller claims can be handled directly with the insurer. The calculus changes when injuries are serious, fault is disputed, the at-fault driver is uninsured, or your own insurer is delaying or undervaluing your claim. These cases often involve multiple policies, stacking questions, and coverage disputes that are difficult to resolve without experience.
An attorney can investigate all available coverage, preserve evidence before it disappears, coordinate medical treatment and liens, and negotiate with both the at-fault driver's insurer and your own. If your insurer acts in bad faith, a lawyer can also advise on remedies that go beyond the policy limits. Because fault rules and insurance requirements vary by state, a local attorney is usually best positioned to evaluate your specific claim.
If you would like to explore your options, you can request a free, confidential case review through AutoInjuryAccident.com. There is no cost to ask, no obligation to move forward, and no pressure to hire anyone. Whether you ultimately handle the claim yourself or work with counsel, the key is to act quickly, document thoroughly, and never accept a settlement before you understand the full picture of your damages and the coverage available to pay them.