Uninsured Motorist Coverage Explained for Accident Claims
Uninsured motorist coverage explained for accident claims: learn how UM and UIM pay when the at-fault driver has no insurance or too little coverage.
By Marcus Hale
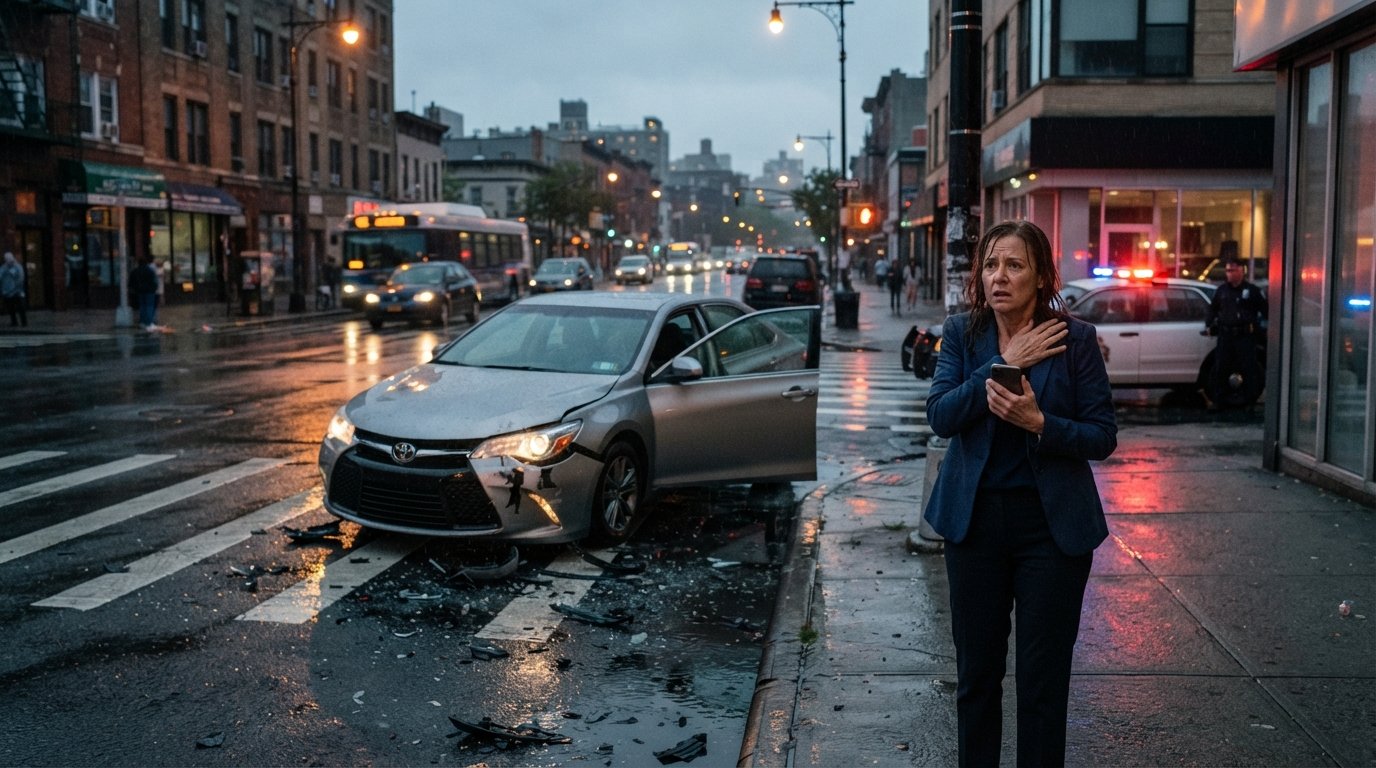
A driver runs a red light, slams into your car, and flees. Another driver has a policy, but it is the state minimum, far too small to cover your surgeries and lost wages. A third driver has no license and no insurance at all. These are the moments when uninsured motorist coverage stops being a line item on a declarations page and becomes the difference between financial recovery and financial ruin. Most drivers know they are required to carry liability insurance, but far fewer understand what happens when the at-fault driver has none, or not enough. This guide walks through how uninsured motorist coverage works, how it interacts with underinsured motorist coverage, what steps to take after a crash, and how these claims are actually resolved, so you can protect your recovery when the other driver cannot.
What Uninsured Motorist Coverage Actually Pays For
Uninsured motorist coverage, often shortened to UM, is a type of auto insurance that applies when you are injured in an accident caused by a driver who has no liability insurance. It can also apply in a hit and run, where the at-fault driver cannot be identified, or when a driver has insurance but the policy has lapsed or been canceled. In many states, UM is mandatory, meaning insurers must offer it and you must actively reject it in writing if you do not want it. In other states, it is optional but highly recommended.
The core purpose of UM is to step into the shoes of the missing or non-existent liability policy. Instead of pursuing the at-fault driver directly, you file a claim with your own insurer under the UM portion of your policy. That does not mean your insurer is admitting fault or that the other driver is off the hook. It simply means your own coverage responds when the responsible party cannot pay. UM can cover medical bills, lost wages, pain and suffering, and other damages that would normally be paid by the at-fault driver's liability coverage.
UM is not the same as collision coverage. Collision pays to repair or replace your vehicle, regardless of fault, minus your deductible. UM pays for bodily injury and, in some states, property damage caused by an uninsured driver. Many drivers assume their collision coverage will handle everything after a hit and run, but collision does not pay for medical bills, lost income, or pain and suffering. That is where UM becomes essential.
There is also underinsured motorist coverage, often abbreviated UIM. UIM applies when the at-fault driver has liability insurance, but the limits are too low to cover your total damages. For example, if the other driver carries a $25,000 per person liability limit and your medical bills and lost wages total $80,000, UIM can make up the difference, up to your own UIM limits. In many policies, UM and UIM are bundled together, but the distinction matters when you are trying to understand which coverage applies to your situation.
How UM and UIM Differ in Practice
The practical difference between UM and UIM comes down to whether the at-fault driver has any insurance at all. If the driver has no policy, no valid license, or flees the scene, UM applies. If the driver has a policy but it is insufficient, UIM applies. Some states treat them as a single coverage, while others require separate elections. Your insurer will typically ask you to provide the at-fault driver's insurance information, police report, and medical records before it evaluates a UM or UIM claim.
Another key point: UM and UIM claims are still claims against an insurance company, and that insurer has an interest in minimizing what it pays. Even though you are filing with your own carrier, the process can become adversarial. This is why documentation and, in many cases, legal guidance matter from the very beginning.
Why Uninsured Motorist Claims Are More Common Than Drivers Expect
The Insurance Research Council has estimated that roughly one in seven drivers nationwide is uninsured, and in some states the rate is significantly higher. That means the odds of being hit by an uninsured or underinsured driver are far from negligible. Even drivers who carry insurance may let it lapse, drive without a valid license, or carry only the minimum limits required by law. In a serious accident, those minimum limits can be exhausted quickly by emergency room bills alone.
There is also the hit and run problem. A driver who flees the scene may never be identified. Without UM coverage, an injured victim in a hit and run may have no path to compensation for pain, suffering, and lost wages, even if the crash was entirely the other driver's fault. UM coverage fills that gap by allowing the victim to pursue a claim with their own insurer as if the missing driver had been insured.
Even when the at-fault driver is identified and has insurance, the policy may be minimal. Many states require only $25,000 or $30,000 per person in liability coverage. A single night in a hospital, an ambulance ride, and follow-up imaging can exceed that amount. Once the at-fault driver's policy is exhausted, UIM coverage becomes the next source of recovery. Without UIM, the injured person may be left with unpaid bills and no way to recover the difference.
This is why many personal injury attorneys and consumer advocates recommend carrying UM and UIM limits that match or exceed your own liability limits. The cost is often modest compared to the protection it provides, and it is one of the few types of insurance that directly protects you and your family when another driver fails to carry adequate coverage.
Steps to Take After an Accident With an Uninsured or Underinsured Driver
The steps you take immediately after a crash can have a significant impact on whether your UM or UIM claim succeeds. The goal is to preserve evidence, document your injuries, and put your insurer on notice as quickly as possible. Because UM and UIM claims are contractual claims against your own policy, they come with notice requirements and deadlines that vary by state and by policy.
Here is a practical sequence that applies in most situations:
- Call 911 and request a police report. Even if the other driver leaves the scene, a police report creates an official record of the crash, the description of the other vehicle, and any witness statements. This is critical for a hit and run UM claim.
- Exchange information if it is safe to do so. Get the other driver's name, contact information, license plate, and insurance details if they are willing to provide them. If they cannot or will not, note that in your report.
- Seek medical attention promptly. Some injuries, including whiplash, concussions, and internal injuries, do not show symptoms immediately. A medical evaluation creates a record linking your injuries to the crash.
- Notify your own insurer. Report the accident and state that you may be filing a UM or UIM claim. Ask what documentation they require and what deadlines apply.
- Document everything. Take photos of the vehicles, the scene, your injuries, and any property damage. Keep copies of medical bills, pay stubs, and correspondence with insurers.
After those initial steps, the claim process becomes more structured. Your insurer will likely assign an adjuster, request medical records and bills, and may ask for a recorded statement. You are generally required to cooperate with your insurer under the terms of your policy, but you are not required to accept a low offer or to sign away your rights. If the insurer disputes the claim, delays payment, or makes an offer that does not cover your damages, you may need to pursue arbitration or litigation, depending on your policy and state law.
Because UM and UIM claims involve your own insurer, some people assume they will be handled fairly and quickly. In reality, these claims can be just as contested as claims against another driver's insurer. The stakes are high, and the insurance company has a financial incentive to pay as little as possible. Having a clear record and, when necessary, legal representation can make a substantial difference in the outcome.
How UM and UIM Claims Are Evaluated and Paid
When you file a UM or UIM claim, your insurer will investigate the accident and evaluate your damages. The insurer will typically look at the police report, witness statements, medical records, and any evidence of the other driver's insurance status. For a UIM claim, the insurer will also want proof of the at-fault driver's liability limits, often through a declaration page or a letter from that driver's insurer.
Damages in a UM or UIM claim generally fall into two categories: economic and non-economic. Economic damages include medical expenses, lost wages, and out-of-pocket costs. Non-economic damages include pain and suffering, emotional distress, and loss of enjoyment of life. The available coverage is capped by your UM or UIM limits, and in some states, those limits can be reduced by amounts already paid by the at-fault driver's insurer or by other sources such as workers' compensation or health insurance.
One of the most important concepts in UM and UIM claims is the consent to settle clause. Many policies require you to obtain your insurer's consent before settling with the at-fault driver's insurer. If you settle without that consent, your insurer may argue that it has been prejudiced and reduce or deny your UIM claim. This is a common trap for people who try to handle the entire process on their own.
If your insurer accepts the claim, it will pay the agreed amount, up to your policy limits. If it denies the claim or disputes the value, the next step depends on your policy and state law. Many policies include arbitration provisions, which require disputes to be resolved through binding arbitration rather than a jury trial. Others allow you to file a lawsuit against your own insurer for breach of contract or bad faith. The specific path depends on your policy language and the law in your state.
Common Mistakes That Undermine Uninsured Motorist Claims
Even when UM or UIM coverage is available, claimants can unintentionally weaken their position. One of the most common mistakes is failing to report the accident to the insurer promptly. Policies typically require notice within a reasonable time, and delays can give the insurer grounds to deny the claim. Another mistake is giving a recorded statement before fully understanding the extent of the injuries or the available coverage.
Another frequent problem is settling with the at-fault driver's insurer without notifying your own insurer or obtaining consent, as mentioned earlier. That can jeopardize your UIM claim and reduce your total recovery. Similarly, failing to document lost wages, medical treatment, and other expenses can lead to a lower settlement than your case is worth.
Finally, many people assume that because they are filing with their own insurer, they do not need legal help. That assumption can be costly. Insurers handle these claims every day, and they know how to evaluate them in their own favor. An experienced attorney can gather evidence, negotiate with the insurer, and, if necessary, pursue arbitration or litigation to recover the full value of your claim.
When to Consider Legal Help for a UM or UIM Claim
Not every UM or UIM claim requires an attorney. A minor accident with limited medical bills may be resolved directly with the insurer. But certain factors suggest that legal guidance is worth considering. These include serious injuries, disputed liability, a hit and run with no identified driver, a low or delayed settlement offer, or a denial of coverage. In those situations, an attorney can investigate the crash, identify all available insurance policies, and negotiate on your behalf.
If you are searching for legal information and a way to connect with attorneys who handle uninsured motorist claims, a resource like LawyerOffer can help you understand your options and request a review of your situation. For those who prefer to start with a free, confidential case review through a consumer matching service, AutoInjuryAccident.com connects injured people with participating attorneys who advertise on the site. It is not a law firm or lawyer referral service, and submitting a form does not create an attorney-client relationship or obligate anyone to hire a lawyer. It simply provides a way to request a no-cost review of your accident and insurance situation.
Deadlines for UM and UIM claims, personal injury lawsuits, and insurance notice vary by state, so acting promptly is important. Evidence can disappear, witnesses can become hard to reach, and memories fade. The sooner you understand your coverage and your legal options, the better positioned you are to protect your recovery.
Protecting Yourself Before the Next Crash
One of the most valuable steps you can take is to review your own auto policy before an accident happens. Check whether you have UM and UIM coverage, and confirm the limits. If you only carry the state minimum, consider whether higher limits make sense for your situation. The difference in premium is often small compared to the potential difference in recovery after a serious crash.
Keep a copy of your declarations page in your vehicle or on your phone, and know how to report a claim. If you are involved in a crash, follow the steps outlined above, document everything, and do not assume the other driver's insurance will take care of it. Uninsured motorist coverage exists precisely because that assumption is unreliable.
Uninsured and underinsured motorist claims can be complex, but they are also one of the most important protections available to drivers. Understanding how they work, what they cover, and how to pursue a claim can mean the difference between struggling with unpaid bills and recovering the compensation you need to move forward.