What Is a Diminished Value Claim After a Car Accident?
A diminished value claim after a car accident recovers the drop in your vehicle's resale value, even after perfect repairs. Learn how to pursue it and what evidence you need.
By Elena Vasquez
A car accident can leave you with injuries, repair bills, and a vehicle that never feels quite the same. Even after the body shop restores your car to its pre-accident condition, something invisible may still be lost: its market value. That hidden loss is exactly what a diminished value claim is designed to address. If you have ever wondered what is a diminished value claim after a car accident, the short answer is that it is a legal demand for the difference between what your vehicle was worth before the crash and what it is worth afterward, even after a perfect repair. This article explains how diminished value works, who can claim it, how insurers evaluate it, and what steps you can take to protect your financial recovery.
Understanding Diminished Value in Plain Terms
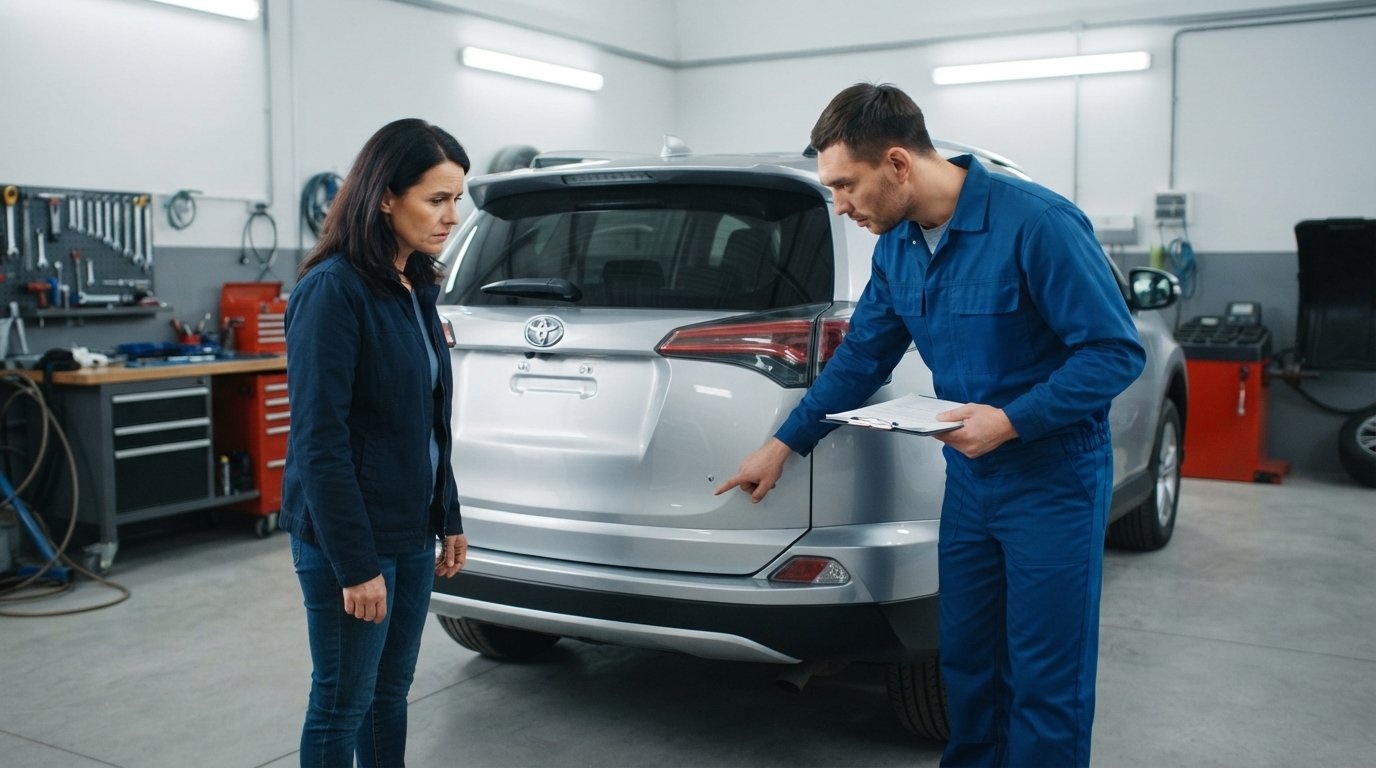
Diminished value is the reduction in your vehicle's resale or trade-in value that results from having a documented accident history. Imagine two identical 2022 SUVs parked side by side. One has a clean vehicle history report, and the other shows a rear-end collision with frame repair. Even if the repaired SUV looks flawless, most buyers will pay less for it because they fear hidden problems, future mechanical issues, or a difficult resale. That price gap is the diminished value.
Insurance companies typically divide diminished value into three categories. Immediate diminished value is the loss that exists the moment the accident happens, before any repairs are made. Repair-related diminished value reflects the loss caused by the quality or extent of the repairs themselves, such as mismatched paint or aftermarket parts. Inherent diminished value is the most common and most argued category: it assumes the repair was done perfectly, yet the vehicle still carries a permanent stigma because the accident appears on its history report.
Understanding these categories matters because insurers often try to lump them together or deny them outright. When you ask what is a diminished value claim after a car accident, you are really asking whether the at-fault party's insurer owes you money for that intangible but very real drop in resale value. In many states, the answer depends on who was at fault, what type of claim you are filing, and whether your state recognizes diminished value as recoverable damages.
Who Can File a Diminished Value Claim?
The rules for diminished value claims vary significantly from state to state, which is one reason these claims confuse so many drivers. In general, the strongest diminished value claims belong to accident victims who were not at fault. If another driver caused the crash, you can typically pursue diminished value from that driver's liability insurance as part of your property damage claim. This is known as a third-party claim, and it is the most common path for diminished value recovery.
First-party claims, which you file with your own insurer under your collision coverage, are much harder. Many states and policy language explicitly exclude diminished value from first-party claims, meaning your own insurer may refuse to pay it even though the accident was not your fault. A few states, notably Georgia, have developed specific formulas and legal precedents that make first-party diminished value claims more viable, but even there, insurers frequently dispute the amount.
If you were partially at fault, your ability to recover diminished value may be reduced or eliminated depending on your state's comparative negligence rules. Some states bar recovery entirely if you were even slightly at fault, while others reduce your award proportionally. Because these rules are so state-specific, it is wise to speak with an attorney who understands your local laws before assuming you have no claim or that your claim is worth a specific amount. You can start by requesting a free, confidential case review through a service like AutoInjuryAccident.com, which connects accident victims with participating attorneys nationwide without any obligation to hire.
How Insurers Calculate Diminished Value
There is no single nationwide formula for diminished value, but insurers and courts commonly rely on a few accepted methods. The most widely cited is the 17c formula, which originated from a Georgia court case and is still used by many insurers as a starting point. The 17c method caps the base loss at 10 percent of the vehicle's pre-accident value, then applies a damage multiplier (usually between 0.25 and 1.0 based on the severity of the damage) and a mileage multiplier (based on your odometer reading).
The problem with the 17c formula is that it often produces lowball figures that do not reflect real market conditions. A more accurate approach involves comparing your vehicle to similar cars with clean histories. This market-based analysis looks at actual listings, auction results, and dealer trade-in quotes for the same make, model, year, and mileage, both with and without accident history. The difference between those two price points is your diminished value.
Other factors that affect the calculation include the age and mileage of your vehicle, the severity of the damage, whether the repair involved structural or frame damage, the quality of the repair, and the demand for your specific make and model in your local market. A brand-new luxury car with frame damage might lose thousands of dollars in value, while an older economy car with minor cosmetic damage might lose very little. Documentation is everything: without repair records, before-and-after valuations, and market comparisons, your claim is just a number without support.
Steps to Build a Strong Diminished Value Claim
Filing a diminished value claim is not as simple as sending a letter to the insurer and waiting for a check. You need evidence, persistence, and a clear understanding of the process. The following steps can help you build a claim that stands up to insurer pushback and positions you for a fair recovery.
- Document everything immediately. Take photos of the damage before repairs, keep all repair estimates and invoices, and save the police report and the other driver's insurance information. This documentation establishes the accident and the scope of the damage.
- Get your vehicle repaired properly. Use a reputable body shop and insist on OEM parts when possible. A high-quality repair reduces the argument that your car suffered additional repair-related diminished value.
- Obtain a professional diminished value appraisal. An independent appraiser who specializes in diminished value can produce a written report that compares your car to similar vehicles and quantifies the loss. This report becomes the backbone of your claim.
- Submit a written demand to the at-fault insurer. Include your appraisal, repair records, and a clear explanation of your state's law on diminished value. Be specific about the amount you are requesting and why.
- Negotiate or escalate if denied. If the insurer refuses to pay or makes a low offer, you may need to file a complaint with your state insurance department, invoke appraisal clauses in your policy, or consult an attorney about filing a lawsuit.
Each of these steps takes time, and insurers know that many claimants give up before reaching a resolution. That is why having professional guidance can make a significant difference. An attorney familiar with diminished value claims can handle the appraisal, communicate with the insurer, and, if necessary, pursue litigation. If you are unsure where to start, a free case review can help you understand your options without any upfront cost. For a broader look at how the initial consultation process works, see this guide on how to request a free car accident case review.
Common Obstacles and How to Overcome Them
Insurers deny diminished value claims for a variety of reasons, and understanding their tactics can help you respond effectively. One common denial is that the vehicle was repaired to pre-accident condition, so no loss exists. In reality, a perfect repair does not erase the accident history, and buyers consistently pay less for cars with reported damage. Another frequent argument is that diminished value is not recoverable in your state, which may or may not be true depending on where you live and whether you are filing a first-party or third-party claim.
Insurers may also dispute your appraisal, arguing that it is speculative or that the appraiser used unrealistic comparables. To counter this, make sure your appraisal relies on verifiable market data, such as recent sales of similar vehicles, dealer quotes, and auction results. If the insurer refuses to budge, you can request an independent appraisal through your policy's appraisal clause, which is a dispute resolution process that does not require going to court.
Another obstacle is the statute of limitations. Every state sets a deadline for filing property damage claims, and missing it can bar your recovery entirely. These deadlines can range from one to several years, so it is important to act promptly. If you are dealing with injuries as well as property damage, the clock may be running on both claims. Consulting an attorney early helps ensure you do not miss any critical deadlines.
The Role of an Attorney in Diminished Value Claims
While you can file a diminished value claim on your own, having an attorney involved often leads to a better outcome. Attorneys understand the nuances of state law, know how to challenge insurer calculations, and can apply pressure that individual claimants cannot. They can also coordinate your diminished value claim with your personal injury claim, ensuring that you do not accidentally waive your rights by accepting a settlement that covers only repairs.
Many accident victims worry that hiring a lawyer is too expensive or complicated. In reality, most personal injury and property damage attorneys work on a contingency fee basis, meaning you pay nothing unless they recover money for you. The initial consultation is typically free, and there is no obligation to hire. If you are looking for a lawyer in your area, you can use a directory service such as TheLawyerDirectory to find attorneys who handle diminished value and related claims. This can be especially helpful if you are also navigating other legal matters, such as a DUI charge or a personal injury lawsuit.
It is important to remember that no attorney can promise a specific outcome or settlement amount. Diminished value claims depend on the facts of your case, your state's laws, and the quality of your evidence. What an attorney can do is level the playing field, protect your rights, and give you the best chance at a fair recovery.
Key Takeaways for Accident Victims
Diminished value is a real financial loss that many drivers overlook after a car accident. Even a perfectly repaired vehicle is worth less because of its accident history, and that difference can amount to hundreds or thousands of dollars. If you were not at fault, you may be entitled to recover that loss from the at-fault driver's insurer, though the rules vary by state.
Building a successful claim requires documentation, patience, and often professional assistance. Start by gathering repair records and photos, then consider hiring a diminished value appraiser. If the insurer denies your claim or makes a low offer, do not give up. An experienced attorney can help you push back and pursue the compensation you deserve. To get started, consider requesting a free case review through a trusted matching service that connects you with participating attorneys in your area. There is no cost to ask, and no obligation to hire.