What to Do in the First 24 Hours After a Car Accident
The first 24 hours after a car accident are critical. Follow these steps to protect your health, preserve evidence, and avoid costly mistakes with insurers.
By Elena Vasquez
The first 24 hours after a car accident can shape everything that follows: your health, your insurance claim, and your legal options. In the chaos of a crash, it is easy to skip critical steps or say the wrong thing to an adjuster. This guide walks you through exactly what to do in the first 24 hours after a car accident, hour by hour, so you protect yourself and your recovery. The actions you take now, from calling 911 to preserving evidence, can make the difference between a smooth claim and a prolonged dispute. Whether you were rear-ended at a stoplight or hit by a distracted driver on the highway, the same core steps apply. Read on to learn how to handle the immediate aftermath with confidence.
Step 1: Secure the Scene and Check for Injuries (Hour 0-1)
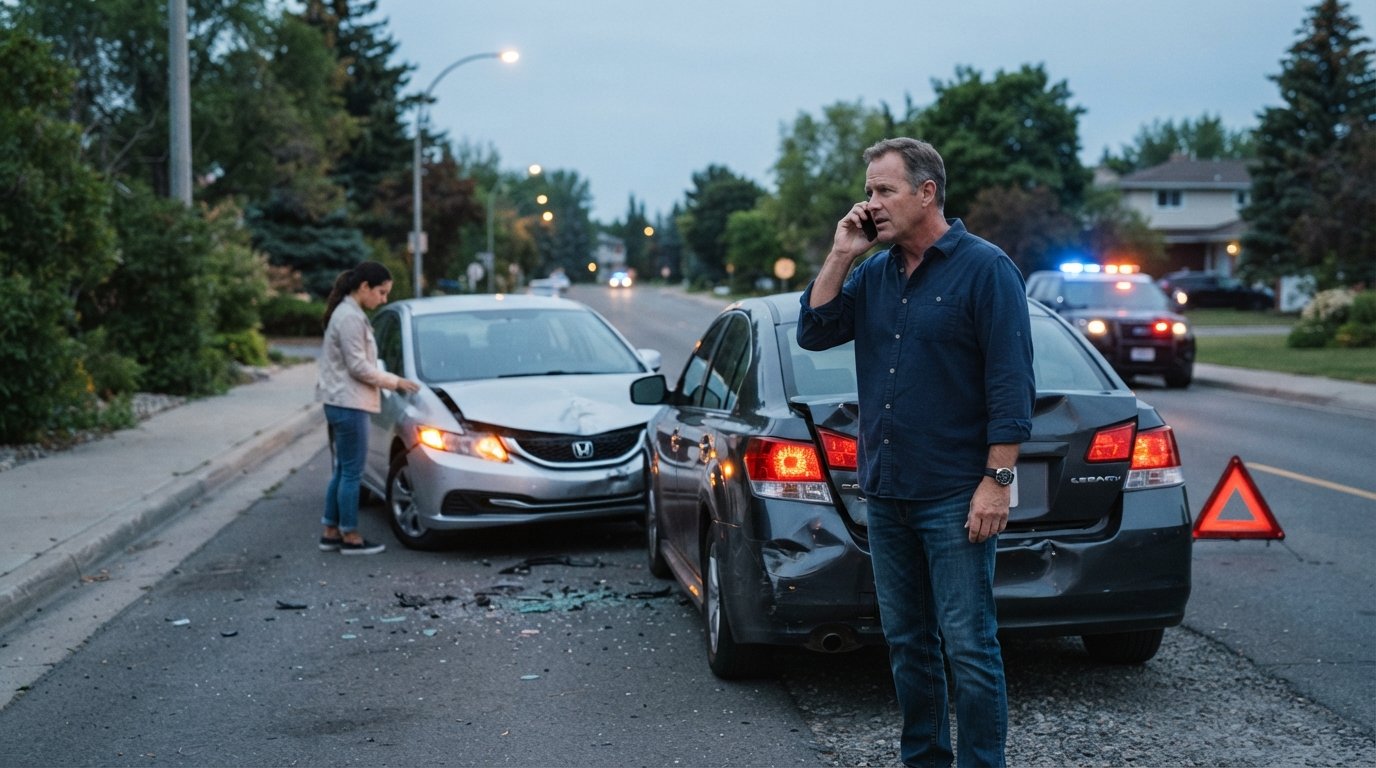
The moments right after impact are the most critical. Your first priority is safety. If you can move safely, pull your vehicle to the shoulder or a nearby parking lot to avoid blocking traffic and reducing the risk of a secondary crash. Turn on your hazard lights and, if you have them, set up reflective triangles or flares. Then, check yourself and your passengers for injuries. Adrenaline can mask pain, so even if you feel fine, be cautious. Call 911 immediately if anyone is hurt, if the other driver appears impaired, or if there is significant property damage. When you speak to the dispatcher, provide your exact location, the number of vehicles involved, and any visible injuries. Do not admit fault or speculate about what happened. Stick to facts: "I was driving north on Main Street when the other car ran the red light." If you are unsure, simply say you are not certain. Remember, anything you say can be used against you later by insurance companies or in court.
While waiting for help, do not leave the scene. Leaving the scene of an accident, especially one with injuries, can lead to criminal charges. If you must move to a safer spot, do so carefully and return as soon as possible. Exchange information with the other driver, but keep the conversation brief and neutral. You will need their name, phone number, insurance company, policy number, and license plate number. If there are witnesses, ask for their names and contact details, but do not discuss the accident with them beyond basic pleasantries. Your goal is to gather facts, not to build a case on the spot. The police will document the scene, but your own notes will be invaluable later.
If you are injured and cannot move, wait for emergency responders. Do not try to be a hero. Moving someone with a suspected spinal injury can cause permanent damage. Once paramedics arrive, follow their instructions and accept transport to a hospital if recommended. Even if you feel okay, a medical evaluation can catch hidden injuries like concussions, whiplash, or internal bleeding. The police will also file an official report, which is a key piece of evidence for your insurance claim. Make sure you get the responding officer's name, badge number, and the report number. This information will help you obtain a copy of the report later. In some states, you are required to report accidents involving injuries or significant damage, so cooperation with law enforcement is essential.
Step 2: Document Everything and Gather Evidence (Hour 1-6)
Once the scene is secure and everyone is safe, your next task is to document the accident thoroughly. Memories fade quickly, and insurance adjusters will look for any gap in your story. Use your smartphone to take photos and videos of the following: all vehicles involved from multiple angles, including close-ups of damage, license plates, and vehicle identification numbers (VINs); the overall scene, including road conditions, traffic signals, and skid marks; your injuries, such as bruises, cuts, or swelling, and any visible damage to your clothing or personal items; and any environmental factors like weather, lighting, or obstructed signs. If you have a dashcam, preserve the footage immediately and back it up to the cloud. Do not delete anything, even if it seems irrelevant.
Collect contact information from everyone involved: the other driver, passengers, witnesses, and the responding police officers. For witnesses, ask if they are willing to provide a statement later. If they agree, get their full name, phone number, and email address. You can also ask them to write down what they saw in their own words. If the police are on scene, they will compile a report, but it may take several days to become available. In the meantime, your own notes will serve as a backup. Write down everything you remember about the accident as soon as possible, including the time of day, the direction each car was traveling, the speed limit, and any statements made by the other driver. Avoid guessing or filling in gaps; stick to what you actually observed.
If you are unable to document the scene due to injuries, ask a trusted friend or family member to help. They can take photos, gather witness information, and even visit the police station to request the report. Many police departments allow you to request reports online or by mail for a small fee. As you gather evidence, keep it organized in a folder or a digital file. This will make it easier to share with your insurance company, your attorney, or a doctor. Remember, insurance companies may try to minimize your claim by arguing that you contributed to the accident or that your injuries are not serious. Strong documentation counters those arguments.
One of the most important pieces of evidence is the police report. It contains the officer's observations, a diagram of the scene, and statements from those involved. While the report is not admissible as evidence in all states, it can still influence how insurers evaluate your claim. If the report contains errors, you can request a correction. Do not delay in obtaining a copy, as some departments have limited retention periods. For a deeper dive into the claims process and how to prepare, consider reading our guide on how to request a free car accident case review, which explains how to connect with attorneys and what to expect.
Step 3: Seek Medical Attention and Follow Doctor's Orders (Hour 6-12)
Even if you feel fine after a car accident, you should see a doctor within the first 24 hours. Conditions like whiplash, concussions, and soft tissue injuries often do not show symptoms until hours or days later. Adrenaline and endorphins can mask pain, so you might not realize you are hurt until the next morning. A timely medical evaluation creates a record that links your injuries to the crash. If you wait too long, the insurance company may argue that your injuries were caused by something else. When you see a doctor, describe all your symptoms, even if they seem minor. Headaches, dizziness, nausea, blurred vision, neck stiffness, back pain, and numbness are all common after a crash. Be honest about your medical history, but do not downplay your discomfort.
Follow your doctor's treatment plan exactly. If they recommend physical therapy, rest, or medication, do it. Skipping appointments or ignoring advice can be used against you in a personal injury claim. Insurance adjusters often hire private investigators to monitor plaintiffs, looking for evidence that they are not as injured as they claim. If you are seen lifting heavy objects or playing sports while claiming a back injury, your credibility will suffer. Keep a daily journal of your symptoms, treatments, and how the injuries affect your daily life. This pain journal can be powerful evidence if your case goes to court. Note the date, time, and intensity of your pain, as well as any activities you had to miss, such as work, school, or family events.
If you do not have health insurance or cannot afford a doctor, many communities have clinics that offer sliding-scale fees. Some personal injury attorneys can also refer you to medical providers who will treat you on a lien basis, meaning they get paid from your settlement. However, be cautious: not all lien-based providers are reputable, and you should always prioritize your health over legal strategy. If you are unsure where to turn, contact a local bar association or legal aid organization for guidance. The key is to get evaluated and start treatment as soon as possible. Delaying medical care not only harms your health but also weakens your legal claim.
Step 4: Notify Your Insurance Company and Handle Their Questions (Hour 12-24)
You should report the accident to your own insurance company within 24 hours, or as soon as your policy requires. Most policies have a clause requiring "prompt" notification, and failing to do so can give the insurer grounds to deny coverage. When you call, stick to the basic facts: the date, time, location, and a brief description of what happened. Do not speculate about fault or say you are sorry. Even a simple "I'm sorry" can be interpreted as an admission of guilt. If the adjuster asks for a recorded statement, you are not obligated to give one immediately. You can say, "I need to consult with an attorney before providing a statement." Insurance companies often use recorded statements to catch inconsistencies and reduce payouts. It is wise to speak with a lawyer before giving any recorded statement, especially if you are injured.
The other driver's insurance company may also contact you. They might offer a quick settlement or ask you to sign a release. Do not sign anything or accept any money without first understanding the full extent of your injuries and damages. Once you sign a release, you cannot seek additional compensation later, even if your condition worsens. If the other insurer calls, be polite but firm: "I am not ready to discuss a settlement. Please direct all further communication to my attorney." If you do not have an attorney, you can simply say you are still evaluating your options. Keep a log of all phone calls, including the date, time, name of the person you spoke with, and a summary of what was said. This log can be useful if there is a dispute later.
Your own insurance company may also offer additional coverage, such as personal injury protection (PIP) or uninsured motorist coverage. PIP can pay for medical bills and lost wages regardless of who was at fault, but it varies by state. Uninsured motorist coverage protects you if the at-fault driver has no insurance or flees the scene. Review your policy to understand what is available. If you are unsure, ask your adjuster to explain the coverage in plain language. Do not let them pressure you into a quick settlement. You have time to gather information and make an informed decision. If you feel overwhelmed, consider contacting a personal injury attorney who can handle these communications on your behalf. Many offer free consultations and work on a contingency fee basis, meaning you pay nothing unless they recover money for you.
If you are considering legal representation, you can use a resource like AttorneyDirectory.Lawyer to find lawyers in your city and request a quote. This directory connects you with attorneys who handle car accident cases and can advise you on the next steps, including how to deal with insurance adjusters and whether to file a lawsuit. Remember, you are not obligated to hire anyone, and the initial consultation is typically free.
Step 5: Avoid Common Mistakes That Hurt Your Claim
Even well-intentioned accident victims can accidentally sabotage their claims. One of the biggest mistakes is posting about the accident on social media. Insurance adjusters routinely check Facebook, Instagram, and Twitter for photos or comments that contradict your injury claims. A picture of you hiking or dancing could be used to argue that you are not seriously hurt. The safest approach is to stay off social media entirely until your case is resolved. If you must use it, adjust your privacy settings and avoid mentioning the accident or your injuries. Another common mistake is delaying medical treatment. As mentioned earlier, gaps in treatment give insurers ammunition to dispute your injuries. Even if you feel better after a few days, keep your appointments and follow your doctor's advice.
Another error is admitting fault, even casually. You might say, "I didn't see them coming," which could be twisted into an admission of negligence. Fault is a legal determination, and in many states, comparative negligence rules mean that even if you were partially at fault, you can still recover damages. But admitting fault can reduce your compensation. Let the investigators and attorneys sort out liability. Similarly, do not agree to a settlement before you know the full extent of your injuries. Some injuries, like traumatic brain injuries or spinal cord damage, may not be fully apparent for weeks or months. Once you sign a release, you cannot go back for more money. Always consult with an attorney before accepting any offer from an insurance company.
Finally, do not try to handle everything alone if you are seriously injured. The insurance process can be complex and stressful, and insurers have teams of adjusters and lawyers working to minimize payouts. You are entitled to legal representation, and in most cases, you do not pay unless you win. If you are unsure whether you need a lawyer, consider a free case review. Many law firms offer this service, and it can give you peace of mind. Remember, the first 24 hours are just the beginning; the actions you take in the days and weeks that follow also matter. But by following the steps above, you set yourself up for a stronger claim and a better recovery.
Taking the right steps in the first 24 hours after a car accident is about protecting your health and your rights. From securing the scene and documenting evidence to seeking medical care and notifying your insurer, each action builds a foundation for your recovery. If you are ever unsure, reach out to a qualified attorney who can guide you through the process. You do not have to face the aftermath alone.