Lost Earning Capacity vs Lost Wages After a Crash
Lost earning capacity versus lost wages after a crash: understand the difference and the evidence that protects your claim. Call (855)-545-2917 for a free case review.
By Julia Hayes
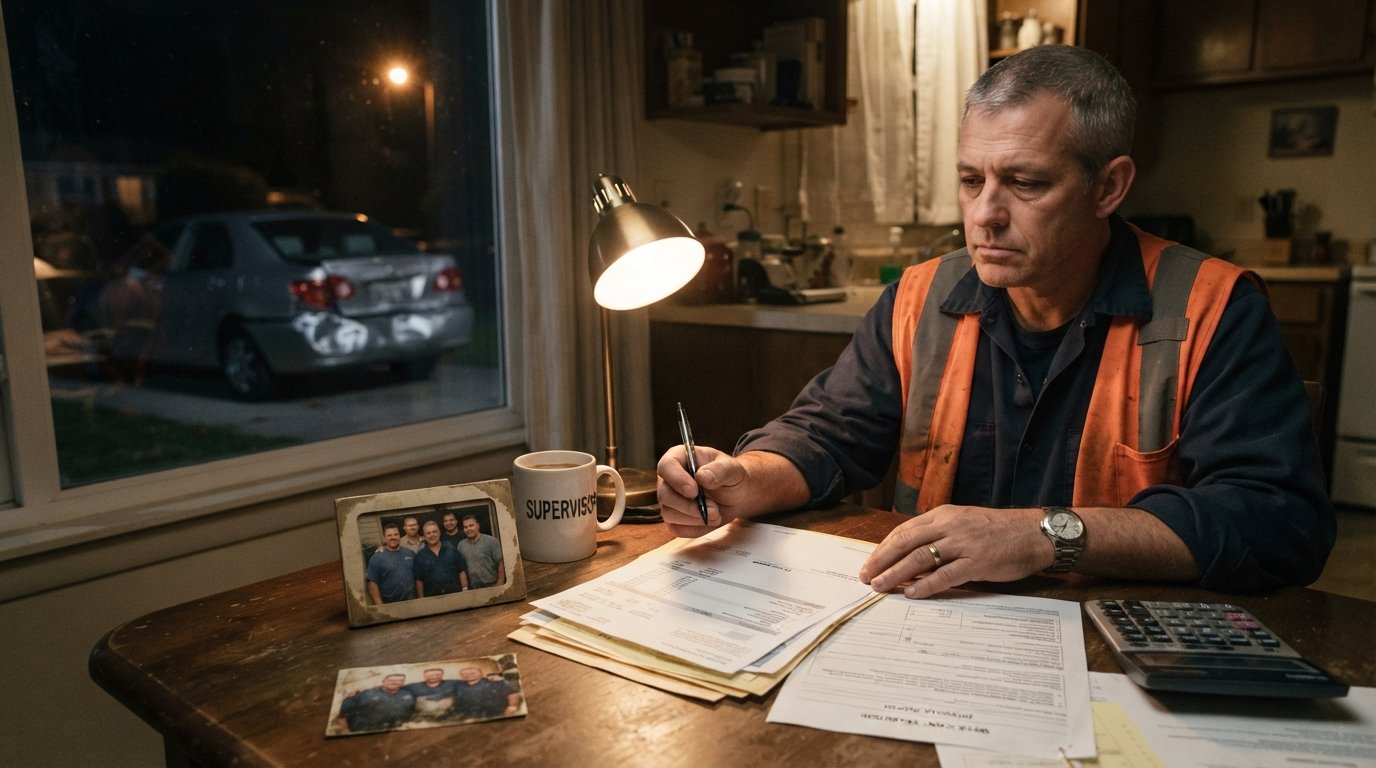
You missed three weeks of work after a rear-end collision, and the adjuster already offered to reimburse those paychecks. But what about the promotion you were up for, or the overtime you can no longer handle because of back pain? That gap between what you lost and what you will lose is where lost earning capacity versus lost wages after a crash becomes the central question in your claim. Understanding the distinction helps you document the right evidence, ask the right questions, and avoid settling for a fraction of what your future may be worth.
Two Different Losses, Two Different Burdens
Lost wages are the easier concept: they are the income you would have received between the date of the crash and the date of settlement or trial if you had been able to work. If you earn $1,200 per week and your physician kept you off work for six weeks, your lost wages claim starts at $7,200, subject to proof and any offsets. Pay stubs, timecards, and employer letters usually carry the day.
Lost earning capacity is broader and often more valuable. It measures the difference between what you could have earned absent the injury and what you can now earn in the open labor market, considering your age, education, skills, medical restrictions, and the trajectory of your career. A 35-year-old warehouse supervisor with a lifted weight restriction may return to a desk job at lower pay; the difference over a working lifetime can dwarf the paychecks missed during recovery.
The two claims overlap but are not interchangeable. Lost wages look backward to actual missed income. Lost earning capacity looks forward to diminished potential, whether or not you have missed a single shift yet. An injured worker who returns to the same job at the same rate can still have a viable capacity claim if the injury forecloses overtime, advancement, or a planned career move. That is why attorneys treat lost earning capacity versus lost wages after a crash as separate lines of proof rather than a single damage figure.
Collision Examples That Show the Difference
Concrete scenarios make the distinction clearer. Consider a restaurant server who suffers a shoulder injury in a side-impact crash. She misses eight weeks of shifts, which is her lost wages claim. Her surgeon later limits her to lifting no more than ten pounds above shoulder height, and she can no longer carry trays or work the busy dinner rush. Even if she finds a hostess position at lower hourly pay, her lost earning capacity claim captures the difference between her pre-crash earnings trajectory and her diminished future earnings.
Now consider an independent contractor who drives for a rideshare platform. His lost wages are the net fares he can prove he would have earned during recovery, which requires platform statements and expense records. His lost earning capacity claim may consider whether the injury prevents him from driving long shifts at all, whether he must reduce his hours permanently, and whether his vehicle modifications or retraining create additional economic loss. Because his income fluctuates, documentation becomes the battleground.
A third example involves a young apprentice electrician. He misses twelve weeks of work, which is straightforward. But his back injury may prevent him from completing the physical requirements of his trade, forcing a switch to a lower-paying role. A vocational expert can project the lifetime earnings differential between the two paths, and that projection often drives the settlement value far more than the missed weeks themselves.
Evidence That Proves Lost Wages
Lost wages claims rise or fall on records. Start with the basics: pay stubs covering the period before and after the crash, W-2 forms, and employer wage statements. If you were hourly, timecards or scheduling records show the shifts you missed. If you were salaried, an employer letter confirming your leave and pay rate works well. Self-employed workers should gather invoices, bank deposits, tax returns, and profit-and-loss statements that show what the business earned before the injury and what it lost during recovery.
Physician notes matter here too. A doctor's written restriction taking you off work, with specific dates, ties your absence to the crash rather than to choice. If your employer offered light duty and your doctor approved it, records of those arrangements help show mitigation. Gaps in employment history invite questions, so be ready to explain any periods without work before the crash. A clean, organized wage-loss file signals credibility to the adjuster and makes a lowball offer harder to justify.
Keep in mind that lost wages are not automatic. The defense will ask whether you used available sick leave or vacation pay, whether you received disability benefits, and whether you could have worked in some capacity. Your claim should account for those offsets honestly. Transparency here strengthens the rest of your case.
Evidence That Proves Lost Earning Capacity
Earning capacity claims require a wider evidentiary net because they concern the future. Medical evidence comes first: physician restrictions, treatment records, and prognosis statements that describe permanent limitations. A restriction like no lifting over twenty pounds or no prolonged standing is a building block for an economist's projection. Without a doctor's documented limitation, a capacity claim has little foundation.
Then come the vocational facts. Your age, education, work history, and skills define the labor market you would have competed in. Job descriptions that list physical demands help show what you can no longer perform. Performance reviews, promotion records, and pay raises show where your career was heading. If you had a job offer or a training program lined up before the crash, that evidence can be powerful because it shows a concrete path the injury interrupted.
Finally, an economist or vocational expert translates those facts into dollars. The expert may compare your pre-injury earnings trajectory with your post-injury capacity, apply work-life expectancy tables, and discount the result to present value. The defense will often hire its own expert to dispute assumptions about future raises, retirement age, or the availability of suitable jobs. Strong documentation on the front end makes those disputes harder to win.
How Vocational Experts Change the Analysis
A vocational expert is a professional who evaluates whether and how an injury affects a person's ability to work. In a capacity claim, the expert reviews medical records, work history, and education, sometimes conducts testing, and offers an opinion on the jobs you can still perform and the earnings those jobs pay. If your injury forecloses your prior trade but leaves you able to work in a lower-paying field, the expert can quantify the difference.
Vocational input matters most when the career impact is not obvious. A construction worker with a knee injury may not be able to return to heavy lifting, but could he supervise? A nurse with a back injury may move to case management at reduced pay. The expert identifies realistic alternatives rather than assuming disability or assuming full recovery. That realism is what makes the testimony credible to a jury or an adjuster.
Experts also address mitigation. The law generally expects injured people to seek reasonable alternative work, so a capacity claim should account for what you can earn, not just what you lost. An expert who acknowledges your residual capacity is often more persuasive than one who claims you can never work again. Attorneys use these opinions to frame a settlement range and to prepare for deposition questions about your future.
How Attorneys Evaluate Future Income Loss
When an attorney reviews a capacity claim, the first question is whether the medical records support permanent limitations. Temporary restrictions generate wage-loss claims; permanent ones open the door to capacity claims. The second question is whether the earnings history is stable enough to project. Steady raises, long tenure, and documented promotions make projection easier. Seasonal or gig work requires more careful analysis, often through bank records and platform data.
The third question is causation. Did the crash cause the limitation, or did a pre-existing condition contribute? Defense attorneys look for prior injuries, prior workers' compensation claims, and gaps in treatment. An honest accounting of your medical history, paired with a physician's opinion apportioning cause, keeps the claim defensible. Attorneys also consider state law, because fault rules, damage caps, and deadlines vary nationwide, and a free case review can clarify which rules apply to you.
Finally, attorneys weigh the cost of proof. Vocational and economic experts charge for their time, and their reports take months. For smaller claims, the expense may not be justified. For larger ones, the expert report often pays for itself by anchoring negotiations. A lawyer can help you decide whether a capacity claim is worth pursuing or whether a well-documented wage-loss claim is the better path. If you are unsure where to start, a no-cost case review through CheapInjuryLawyer can connect you with participating attorneys who handle these evaluations, and there is no obligation to hire anyone.
Why Documentation Should Start Early
Evidence fades. Witnesses move, employers change payroll systems, and memories blur. The weeks after a crash are the best time to preserve the records that support both wage-loss and capacity claims. Request your pay stubs and tax returns, ask your employer for a wage verification letter, and keep every physician note that mentions work restrictions. If you are self-employed, start a file of invoices and bank statements now rather than reconstructing them later.
Early documentation also protects against gaps in treatment. Insurance adjusters often argue that a gap suggests you were not seriously injured. Consistent medical care, with restrictions documented in writing, builds the foundation for both types of claims. If you change jobs or return to work with limitations, note the date and the reason. A simple journal of work missed, symptoms, and medical visits can refresh your memory and support your testimony.
Finally, early legal guidance helps you avoid mistakes that are hard to undo. Statements to the adjuster, social media posts about activities, and premature settlements can undercut a capacity claim before it matures. A consultation early in the process lets you understand the difference between lost earning capacity versus lost wages after a crash and plan the evidence accordingly. Many personal injury attorneys work on contingency, so the consultation costs nothing upfront, and submitting a request does not create an attorney-client relationship or require you to hire anyone.
If you were hurt in a crash and are unsure whether your future earnings are at risk, take the time to document your losses and ask questions before you sign anything. The difference between a wage-loss claim and a capacity claim can be substantial, and the evidence you gather now shapes what you can recover later. A free, confidential case review is a practical first step toward understanding your options.