Signs Your Car Accident Injury Claim Is Being Undervalued
Spot the warning signs your car accident injury claim is being undervalued before you sign. Call (855)-545-2917 for a free, confidential case review.
By Thomas Carter
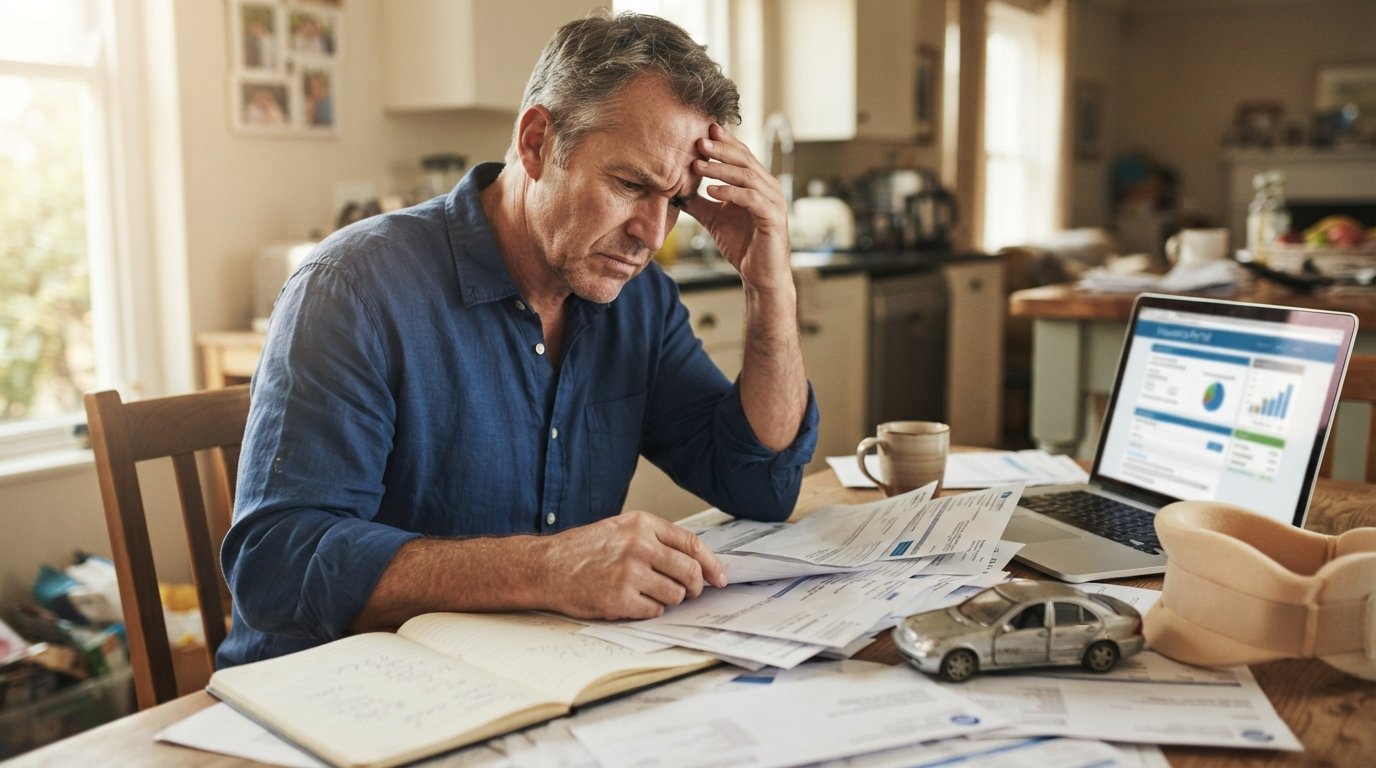
You open the settlement letter expecting progress and instead find a number that barely covers the tow bill, let alone the weeks of chiropractic care, the lost shifts at work, and the ache that still wakes you at 3 a.m. Something feels off, but the adjuster's tone is friendly and the paperwork looks official. Before you sign anything, understand that a low first offer is not a final answer, and it is rarely an accident. Insurance companies are businesses that profit when claims close cheaply, and they have a playbook for making serious injuries look minor on paper.
This guide walks through the concrete, recognizable warning signs that your car accident injury claim is being undervalued. You will learn how adjusters shrink documented injuries, why future medical needs and lost earning capacity quietly vanish from offers, how recorded statements and broad medical authorizations undercut your position, and when a no-cost case review with a participating attorney may be worth your time. AutoInjuryAccident.com is not a law firm and does not provide legal advice, but it does connect injured people nationwide with independent attorneys who can evaluate a claim at no upfront cost. Think of this article as a flashlight, not a legal opinion, and use it to ask better questions before you accept less than your claim may be worth.
How Adjusters Shrink Documented Injury Claims
An adjuster's job is not to be fair in the abstract. It is to resolve your claim for the lowest defensible amount, and the word defensible does a lot of work. Many tactics are not illegal, they are simply designed to create doubt. Doubt about whether your injury is as bad as you say, doubt about whether treatment was necessary, and doubt about whether the accident really caused the problem. Once doubt is planted, the offer shrinks.
One of the most common moves is delay. The adjuster asks for more records, says the file is under review, and lets weeks pass. Meanwhile, you are stressed, behind on bills, and more willing to take whatever is offered. Another tactic is the quick, early offer, sometimes within days of the crash, before you know the full extent of your injuries. A fast check can feel like a blessing, but it often comes with a release that ends your right to seek more later, even if surgery turns out to be necessary.
Adjusters also cherry-pick the medical record. They highlight a gap in treatment as evidence you were fine, ignoring that you could not afford the copay or that your doctor said to return only if symptoms worsened. They describe soft tissue injuries as minor even when the pain is chronic and disabling. They may also suggest that a pre-existing condition, like an old back strain, explains everything, even when your physician documented a new injury at a different level of your spine. Watch for these signals:
- An offer arrives unusually fast, before you have finished treatment or reached maximum medical improvement.
- The adjuster repeatedly asks for the same documents or says the file is still under review without a clear timeline.
- Your medical records are summarized in a way that omits key findings, imaging results, or specialist referrals.
- The adjuster calls your injury minor or soft tissue despite ongoing pain, injections, or physical therapy.
- A pre-existing condition is blamed for symptoms that began or worsened after the crash.
None of these tactics mean your claim is worthless. They mean the first number is a starting position, not a verdict. If you recognize several of these signs, slow down before signing. Ask for a written breakdown of how the offer was calculated, including medical bills, lost wages, and any amount for pain and suffering. If the breakdown is vague or the adjuster resists putting it in writing, that itself is a warning sign that your car accident injury claim is being undervalued.
It also helps to know the difference between economic and non-economic damages. Economic damages are the bills and paychecks you can count: emergency room charges, imaging, surgery, prescriptions, mileage to appointments, and lost income. Non-economic damages cover pain, suffering, emotional distress, and loss of enjoyment of life. Insurers love to pay a portion of the first category and pretend the second does not exist. If your offer covers only some bills and nothing for the months you spent unable to lift your child or sleep through the night, the valuation is incomplete by design.
Why Future Medical Needs and Lost Earning Capacity Get Missed
Most low offers share a hidden flaw: they price your claim as if your recovery ends today. In reality, a serious car accident injury can require years of care, and some never fully resolve. Future medical needs are one of the most frequently undervalued components of a claim because they require documentation that goes beyond the current bill stack. An adjuster will not volunteer to pay for a surgery you might need in two years. You have to prove it is more likely than not.
Lost earning capacity is even easier to overlook. Lost wages are the paychecks you already missed, which are relatively simple to document with pay stubs. Lost earning capacity is the difference between what you could have earned over your career and what you can earn now because of the injury. A delivery driver with a herniated disc may not return to the same route. A nurse with a shoulder injury may not lift patients. A construction foreman with a traumatic brain injury may struggle with the cognitive demands of the job. These losses can dwarf the medical bills, yet they rarely appear in an initial offer unless someone pushes for them.
Proving future losses usually requires expert input. A treating physician can state that you will likely need future care, such as injections, physical therapy, or a replacement procedure. A vocational expert or economist can translate your limitations into a dollar figure. Without that evidence, the adjuster has an easy argument: there is no proof of future harm, so there is no payment for it. That is why accepting a quick settlement before you understand your long-term prognosis is one of the clearest signs your car accident injury claim is being undervalued.
Consider what a complete future-loss evaluation often includes:
- A written opinion from your treating physician about the need for future care and the expected frequency and cost.
- An assessment of permanent restrictions, such as lifting limits, standing limits, or cognitive limitations.
- A vocational analysis of how those restrictions affect your ability to do your prior job or retrain for another.
- Documentation of lost benefits, retirement contributions, and promotional opportunities you can no longer pursue.
- A life care plan for catastrophic injuries that outlines ongoing medical and personal care costs.
If none of this appears in the adjuster's math, the offer is not a full valuation, it is a partial one. You are allowed to ask whether future medical care and lost earning capacity were considered. If the answer is no, or if the adjuster says you can always reopen the claim later, get that in writing and verify it, because many releases close the door permanently. Understanding how these losses are calculated is one reason some injured people choose to speak with an attorney before settling.
For passengers injured in a hired vehicle, the liability picture can be even more layered, and future losses are often missed because fault is disputed. If that situation applies to you, this guide on a rideshare accident injury claim as a passenger explains how coverage and claims can overlap.
Recorded Statements and Blanket Medical Authorizations
Two requests show up early in almost every claim, and both can quietly shrink your recovery: a recorded statement and a broad medical authorization. The adjuster may frame them as routine, even required. In most cases involving the other driver's insurer, you are not legally obligated to give a recorded statement, and you are not obligated to sign a blanket release of all your medical records. Understanding why matters.
A recorded statement is exactly what it sounds like. The adjuster asks questions, you answer, and the recording becomes evidence. The problem is that the questions are designed to lock in a version of events that favors the insurer. You may be asked whether you felt fine at the scene, whether you had any prior injuries, or whether you have returned to your normal activities. A casual yes can later be used to argue you were not seriously hurt. You might also be asked about gaps in treatment or about a previous accident, and a tired or medicated answer can be clipped and replayed out of context.
A blanket medical authorization is similarly one-sided. It lets the insurer request all of your medical records, often going back years and covering unrelated conditions. That gives the adjuster ammunition to argue that your headaches are from a prior migraine history or that your back pain is degenerative rather than traumatic. A narrow authorization limited to records from the accident and specific providers is usually sufficient for the insurer to evaluate the claim. If the adjuster insists on everything, ask why and consider whether the request is reasonable.
Watch for these pressure points around statements and authorizations:
- The adjuster calls within days of the crash and asks to record the conversation.
- You are told a recorded statement is mandatory before any offer can be made.
- The authorization form has no end date and no limit on which providers can be contacted.
- The adjuster asks about prior accidents, prior injuries, or unrelated medical conditions in detail.
- You are encouraged to sign quickly because the offer might expire.
You can politely decline a recorded statement and offer to provide a written summary instead. You can also ask for a limited authorization that covers only the treatment related to the crash. If the adjuster refuses, that refusal is information. It suggests the insurer wants access it would not otherwise get. At that point, a no-cost case review with a participating attorney may help you understand your rights and whether the request is standard in your state, since rules vary nationwide.
Legal consumers also face related pressure in other areas of law, including disputes with their own lawyers over fees or representation. If you are researching how attorney-client disputes work, resources such as AttorneyLawsuit publish educational articles on legal malpractice, fee disputes, and client rights that can help you ask better questions.
When a No-Cost Case Review May Help
Not every undervalued claim needs a lawyer. Some disputes can be resolved by asking for a written breakdown, submitting additional records, or negotiating directly with the adjuster. But there are situations where the gap between the offer and the evidence is wide enough that professional evaluation makes sense, especially because most personal injury attorneys work on contingency, meaning you pay nothing upfront and fees come out of a recovery if one is obtained.
A no-cost case review is not a commitment to hire anyone. It is an opportunity to have an independent attorney look at your records, the adjuster's offer, and the applicable state rules, then tell you whether the claim appears undervalued and what steps might improve it. Because fault rules, insurance requirements, and filing deadlines vary by state, a local perspective matters. A deadline you miss can end the claim entirely, no matter how strong the evidence. AutoInjuryAccident.com is a consumer matching site, not a law firm or lawyer referral service, and it does not provide legal advice, but it does let you request a free, confidential case review from participating attorneys who advertise on the site. Submitting a form does not create an attorney-client relationship and does not obligate you to hire anyone.
Consider a case review if you recognize any of the following:
- The offer does not cover your current medical bills and lost wages, let alone future care.
- You are still treating, or your doctor has recommended surgery, injections, or ongoing therapy.
- You have permanent restrictions that affect your ability to work or perform daily activities.
- The adjuster is pressuring you for a recorded statement or a broad medical authorization.
- You have already signed a release and later discovered additional injuries or losses.
- The statute of limitations in your state is approaching and you have not settled.
A review can also help you avoid a second mistake: signing a release that ends the claim before you know your full prognosis. Once you sign, reopening the claim is usually difficult or impossible. An attorney can explain what you are giving up, whether the offer accounts for future losses, and whether negotiation or litigation could produce a more complete result. There are no guarantees in any claim, and no one can promise a specific outcome, but informed decisions are almost always better than rushed ones.
If you decide to move forward, gather your documents first: the police report, photographs, medical records and bills, pay stubs, and any correspondence from the insurer. A clear file helps any attorney evaluate your claim quickly. If you are not ready to speak with an attorney, you can still protect yourself by declining recorded statements, limiting medical authorizations, and refusing to sign a release until you understand every category of loss. The signs that your car accident injury claim is being undervalued are often hiding in plain sight, and recognizing them is the first step toward a fairer number.