Insurance Company Recorded Statement Request After a Car Accident
An insurer's recorded statement request can shape your injury claim. Learn your rights and call (855)-545-2917 for a free case review.
By Daniel Ortiz
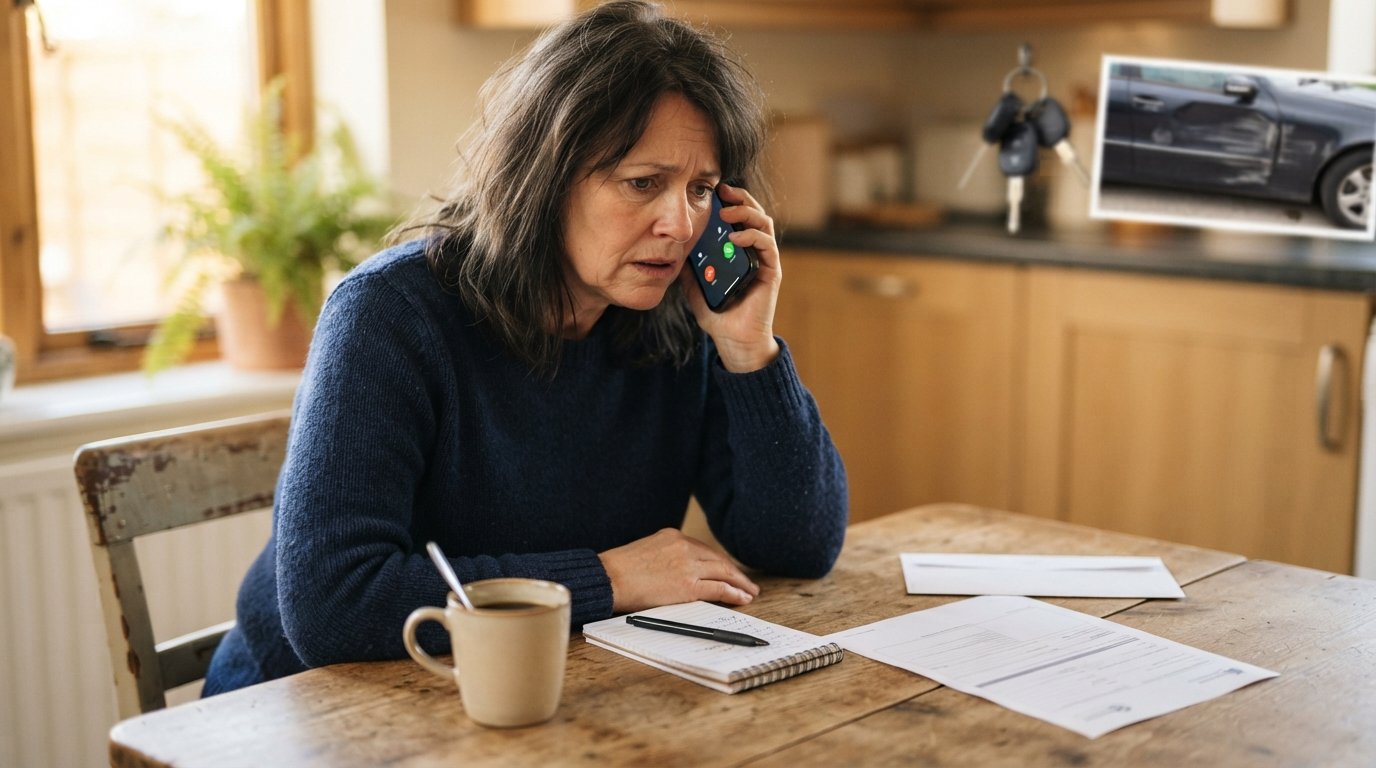
The phone rings a few days after the crash. An adjuster introduces themselves, explains they are handling the claim, and asks if you have a few minutes to give a recorded statement. They sound friendly, organized, and reasonable. That is the moment when many crash victims make a decision that follows them for months: they agree to talk on the record before they understand how that recording will be used.
An insurance company recorded statement request after a car accident is a standard claims step, not a trap in every case. Still, the words you choose, the details you guess at, and the questions you answer can shape how an adjuster values your injury claim. This guide explains why insurers ask, what they do with the recording, when you must cooperate, and how to protect yourself without derailing a legitimate claim.
Why Adjusters Ask for a Recorded Statement After a Crash
Insurance adjusters record statements because a recording is efficient evidence. It captures your account in your own words, close to the date of the crash, before memories fade or stories change. From the carrier's perspective, a recorded statement serves several purposes at once. It locks in your version of events, tests whether your account matches the police report and the other driver's account, and gives the company a baseline for evaluating injuries and liability.
Insurers also use recordings to spot inconsistencies. If you tell the adjuster you felt fine at the scene but later claim significant back pain, the carrier will compare those statements. If you estimate your speed at 40 miles per hour on the recording but the crash reconstruction suggests 55, the discrepancy becomes a bargaining chip. Adjusters are trained to ask open-ended questions first, then narrow questions that probe for admissions. A casual comment like "I probably should have looked twice" can later be characterized as an admission of fault, even if you were mostly describing normal caution.
There is also a financial incentive behind the request. Every recorded statement helps the carrier decide how much to reserve for the claim, whether to accept or dispute liability, and how aggressively to defend a lawsuit if one is filed. The recording is not a neutral customer service call. It is a claims investigation tool, and it is wise to treat it that way.
How Recorded Statements Are Used in Car Accident Claims
Once recorded, a statement can be transcribed, summarized in the claim file, and shared with supervisors, defense counsel, and outside reviewers. In litigation, the recording may be discoverable, meaning the other side can obtain it and use it to cross-examine you later. Even in a claim that never reaches court, the adjuster's notes about your statement influence the settlement offer.
Carriers commonly use recorded statements for three purposes. First, they evaluate liability: who had the right of way, who was distracted, who violated a traffic law. Second, they evaluate damages: how the crash happened, what you felt immediately afterward, whether you went to the hospital, and whether you missed work. Third, they look for inconsistencies that justify a lower offer or a denial. A single offhand remark, such as saying you were "just shaken up" at the scene, can be used to argue that your later medical treatment was unrelated to the crash.
The recording can also help you if your account is accurate and consistent. A clear, honest statement that matches the police report and your medical records can support your credibility. The goal is not to avoid every recorded statement forever. The goal is to give one only when you are prepared, and to answer questions truthfully without speculating.
Risks of Guessing or Speculating on the Call
The biggest danger in a recorded statement is the pressure to answer every question immediately. Adjusters may ask about speed, distance, weather, traffic signals, and your medical history in rapid succession. If you do not know an answer, the safest response is that you do not know or do not recall. Guessing feels helpful in the moment, but a guess on a recording becomes a fact the carrier can hold you to.
Consider a common example. An adjuster asks how fast you were driving. You were in traffic and honestly are not sure, but you say "maybe 35" to be cooperative. Later, a witness says traffic was moving at 20. The carrier now argues you were speeding or inattentive. A better answer would have been: "I was driving with the flow of traffic and I do not have an exact speed." That answer is truthful, responsive, and does not create a harmful admission.
Speculation about your injuries is equally risky. If you say "I do not think it is serious" before seeing a doctor, the carrier will use that statement to challenge later treatment. If you say "I am fine" because you feel embarrassed or want to be polite, the recording will be cited in the claim file. Injuries often take days to appear. It is entirely reasonable to say, "I am still being evaluated and I will follow my doctor's advice."
Other common traps include estimating time and distance ("I stopped about two car lengths back"), describing fault ("I did not see them until the last second"), and discussing prior injuries or accidents without context. You should never lie, but you also do not need to volunteer estimates or opinions you are not sure about.
Your Insurer Versus the Other Driver's Insurer
Not all recorded statement requests carry the same weight. Your own insurer and the other driver's insurer stand in different positions, and your obligations differ accordingly.
Your own carrier usually has a contractual right to investigate a claim. Your auto policy likely includes a duty to cooperate with the investigation. That duty may include giving a statement, submitting to an examination under oath in some circumstances, and providing documents. Refusing outright can jeopardize coverage, especially for collision, personal injury protection, or uninsured motorist benefits. However, the duty to cooperate does not mean you must give a statement immediately, without preparation, or without counsel. You can usually ask for a reasonable delay, request the questions in writing, or have an attorney present depending on your policy and state law.
The other driver's insurer has no contract with you. It cannot compel you to give a recorded statement, and you are generally free to decline or to postpone until you have legal guidance. Adjusters for the at-fault carrier often call early, before you have hired anyone, precisely because an early statement is more likely to contain helpful admissions. You can politely say, "I am not prepared to give a recorded statement right now. Please send your request in writing, and I will follow up." That response is professional and does not harm a legitimate claim.
If you are unsure which insurer is calling, ask. Confirm the company name, the claim number, and whether the adjuster represents your carrier or the other driver's carrier. Write down the date, time, and name of the caller. This simple step prevents confusion later.
What Information You Must Provide Under Policy Duties
Insurance policies vary by state and by carrier, but most include cooperation clauses. These clauses typically require you to report the accident promptly, provide information about the crash, submit to a medical examination when requested, and cooperate in the investigation. A recorded statement may be part of that cooperation, but the scope is usually limited to relevant facts about the accident and your injuries.
You should be prepared to provide basic, factual information such as the date, time, and location of the crash, the vehicles involved, the names of drivers and passengers, and a description of what happened in your own words. You should also be prepared to discuss your injuries at a general level and the treatment you have received. What you do not need to do is speculate, estimate, or offer opinions about fault, speed, or the severity of your injuries before you have medical records.
If your own insurer asks for a recorded statement, review your policy language or ask the adjuster to identify the provision that requires it. Many policies require cooperation but do not specifically require a recorded statement at the first request. A reasonable approach is to say, "I want to cooperate. I need a few days to review my records and consult with counsel, and then I will be glad to schedule the statement." In most cases, a short, reasonable delay will not be treated as a breach of the policy.
If you are dealing with a DUI-related crash or a criminal charge alongside the injury claim, the stakes are higher. Statements made in a civil insurance call can sometimes surface in related proceedings. In that situation, speak with a criminal defense attorney before giving any recorded statement. For general information on how a DUI conviction can affect insurance rates, see our guide on how a DUI conviction affects car insurance rates.
When to Ask for More Time or Legal Guidance
You should strongly consider asking for more time before giving a recorded statement if any of the following apply:
- You have not yet completed a medical evaluation or you are still treating for your injuries.
- The police report is not available or you have not reviewed it.
- The other driver's insurer is calling and you have not spoken with a lawyer.
- You are unsure who was at fault or there are conflicting accounts of the crash.
- You have prior injuries, prior accidents, or a complicated medical history.
- You were arrested or cited in connection with the crash.
In these situations, a short delay is almost always better than a rushed recording. You can say, "I want to give you accurate information. I am not available today, but I will contact you by a specific date." Then follow up in writing so there is a record of your cooperation.
If you are considering legal representation, a free case review can help you understand your options before you speak with an adjuster. AutoInjuryAccident.com is a consumer matching site, not a law firm or lawyer referral service. It connects people injured in car crashes, truck wrecks, and related incidents with participating attorneys who advertise on the site. Requesting a no-cost, confidential review does not create an attorney-client relationship and does not obligate you to hire anyone. You can also use a service such as CheapInjuryLawyer to request a free case review and compare options. Many participating attorneys work on contingency, so injury victims often pay nothing upfront.
How to Prepare for a Recorded Statement If You Decide to Give One
Preparation turns a risky call into a manageable one. Before the recording starts, gather the police report, your insurance card, photos of the damage, and any medical records or discharge papers you have. Review the timeline of the crash and your treatment so your account is consistent. Write a short outline of the key facts: where you were going, what lane you were in, what you saw, what you heard, and what you felt immediately after impact.
During the call, follow a few simple rules. Listen to the entire question before answering. Answer only what is asked, and do not volunteer extra detail. If you do not know an answer, say so. If you need a question repeated, ask. If the adjuster asks about prior injuries, answer truthfully but provide context, such as whether the prior injury had resolved or affected the same body part. If you need a break, ask for one. You can also ask the adjuster to clarify whether the statement is being recorded and how it will be used.
After the call, write down what you remember saying and request a copy of the recording or transcript if possible. If you notice a mistake in your statement, correct it promptly in writing. Accuracy and consistency matter far more than sounding polished.
Finally, remember that you are not required to navigate this process alone. A recorded statement is a routine claims step, but it is also evidence. Treat it with the same care you would give any formal interview, and do not let a friendly tone pressure you into guessing about facts you do not know.