Truck Accident With a Broker Involved: Who Is Liable?
Truck accident with a broker involved? Who is liable for the crash hinges on contracts and control. Call (855)-545-2917 for a free case review today.
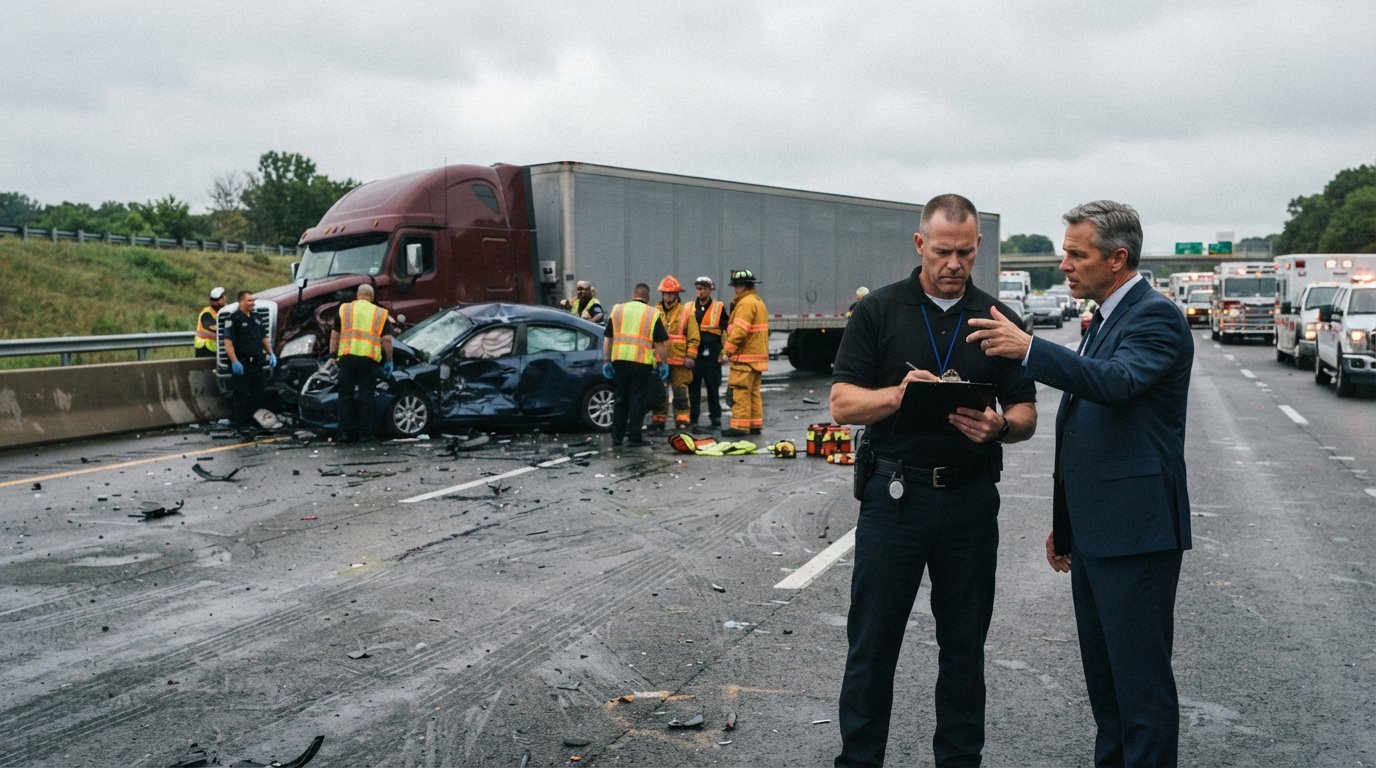
When a semi-truck crashes into your vehicle, the physical damage is often just the beginning. The real battle frequently starts later, when multiple companies point fingers at each other to avoid paying for your injuries. In many of these crashes, a third party is quietly pulling the strings from a desk hundreds of miles away: the freight broker. If you have been hurt in a truck accident with a broker involved, who is liable for the crash is a complex question that hinges on contracts, federal regulations, and the careful preservation of electronic records. Understanding these dynamics is critical because the broker often tries to wash its hands of responsibility, claiming it only arranged the shipment and had no control over the driver.
This article breaks down the legal theories that courts use to hold brokers accountable, the difference between broker and carrier insurance, and the immediate steps you must take to protect evidence. If you are facing mounting medical bills and a confusing web of corporate entities, you do not have to sort through it alone. You can request a free legal case review to speak with an attorney who understands the trucking industry and can help you identify all responsible parties.
The Role of the Freight Broker in a Truck Accident
A freight broker is an intermediary that connects shippers who have goods to move with motor carriers who have trucks available. By law, brokers do not take physical possession of the cargo; they arrange for its transportation. Because brokers are paid a fee or commission for this matchmaking service, they often try to distance themselves from the actual operation of the truck. However, this distance does not automatically shield them from liability when a crash occurs. The central legal question is whether the broker exercised sufficient control over the carrier or the driver to create a duty of care, or whether the broker negligently hired an unsafe carrier.
In a truck accident with a broker involved, who is liable for the crash often depends on the specific actions the broker took before the wheels started rolling. Federal regulations require brokers to exercise reasonable care when selecting carriers. If a broker hires a carrier with a history of safety violations, expired insurance, or a poor safety rating, the broker can be held directly liable for negligent selection. This is a crucial point for victims: the broker cannot simply claim ignorance if the carrier's unsafe history was available in federal databases. Attorneys often investigate whether the broker prioritized cheap rates over safety, cutting corners that led to the collision.
Furthermore, the level of control the broker exerted matters. While a broker typically does not dispatch the truck, some brokers dictate strict delivery schedules that force drivers to speed or violate hours-of-service rules. If a broker pressured a driver to ignore rest breaks to make a delivery window, the broker may share liability for the resulting fatigue-related crash. Proving this requires digging into communications between the broker and the carrier, which is why legal representation is often necessary to obtain subpoenaed records. The nuances of these claims differ significantly from standard auto cases, as explained in our guide on truck accident claim differences from car crash cases.
How Broker and Carrier Contracts Allocate Responsibility
The contractual agreement between the broker and the motor carrier is the first place insurers look when determining fault. These contracts, often called broker-carrier agreements, contain indemnification clauses and insurance requirements. Brokers typically require carriers to name them as additional insureds, meaning the carrier's insurance must cover the broker in the event of a lawsuit. However, these contracts cannot override federal law or public safety obligations. If the broker's own negligence contributed to the crash, a contract clause cannot shield them from a personal injury claim brought by an injured motorist.
In many disputes, the broker will argue that the carrier is an independent contractor and solely responsible for the driver's actions. This defense is strong if the broker can prove it had no operational control. However, the presence of certain clauses in the contract can undermine this defense. For example, if the contract grants the broker the right to inspect the truck, discipline the driver, or dictate specific routes, a court may find that the broker exercised enough control to be considered a joint employer or a principal. The following elements of a broker-carrier contract are critical to review:
- Indemnification clauses: These provisions dictate who pays legal fees and settlements. While often one-sided in favor of the broker, they can sometimes be voided if they violate state law or public policy.
- Insurance requirements: Brokers usually require carriers to carry a minimum amount of liability coverage, often $1 million. If the broker failed to verify this coverage, it may be liable for the resulting damages.
- Safety stipulations: Contracts may require carriers to maintain specific safety ratings. If the broker ignored a carrier's failing safety score, this contract clause becomes evidence of negligence.
- Control provisions: Any language that gives the broker authority over the driver's schedule or route can be used to establish a duty of care.
Beyond the contract, the reality of the relationship matters. Courts look at the "economic realities" of the situation. If the broker effectively controlled the carrier's operations, the independent contractor defense may fail. An experienced attorney will obtain these contracts during discovery to see if the broker breached its own agreement or failed to enforce safety provisions. This is a standard part of the investigation process, but it requires speed, as some contracts include clauses requiring disputes to be resolved in distant jurisdictions, which can complicate a victim's ability to sue locally.
Why Motor Carrier Records and Dispatch Logs Matter
In any truck accident investigation, the motor carrier's records are the goldmine of evidence. When a broker is involved, these records become even more critical because they can reveal the broker's influence on the driver. Dispatch logs, text messages, and phone records can show whether the broker was communicating directly with the driver, bypassing the carrier's safety department. If a broker told a driver to "keep driving" despite bad weather or fatigue, those communications are proof of negligence.
Electronic logging devices (ELDs) are now mandatory in most commercial trucks. These devices record the driver's hours of service, speed, and location. If a crash occurred because the driver was fatigued, the ELD data will show if the driver was pressured to violate rest rules. The broker's records, including load tenders and rate confirmations, can show if the delivery schedule was unrealistic. For example, if a broker accepted a load that required a driver to travel 600 miles in 10 hours (a violation of speed limits and hours-of-service), the broker shares responsibility for the unsafe schedule.
Preserving these records is a race against time. Many trucking companies and brokers have retention policies that allow them to delete electronic data after a short period, sometimes as little as 30 days. Once a spoliation letter (a formal request to preserve evidence) is sent by an attorney, the companies are legally obligated to retain the data. Without this letter, critical dispatch logs or broker communications may vanish. If you are handling this on your own, you risk losing the very evidence needed to prove who is liable for the crash. It is advisable to seek legal help immediately to ensure these records are preserved.
Insurance Coverage Differences Between Brokers and Carriers
One of the most confusing aspects of a truck accident with a broker involved is the insurance puzzle. Motor carriers are required to carry significant liability insurance, often $750,000 to $1 million for general freight. Brokers, on the other hand, are not required to carry the same level of auto liability insurance because they do not operate the trucks. However, brokers usually carry general business liability insurance and contingent auto liability coverage. The difference is that contingent coverage only kicks in if the carrier's insurance is insufficient or denies the claim.
This hierarchy of coverage means that victims often have to pursue multiple claims. The carrier's insurer is the primary source of recovery, but if the carrier is underinsured or goes bankrupt, the broker's insurer may be the next target. Additionally, if the broker was negligent in selecting the carrier, the broker's general liability policy may respond. The challenge is that insurance companies for brokers are aggressive in denying claims, arguing that their insured was not the proximate cause of the crash.
Understanding the insurance limits is vital for maximizing recovery. A common tactic by brokers is to settle quickly with the carrier's insurance for the policy limit, leaving the victim to sign away their rights against the broker. This is a trap. If the carrier's insurance is only $1 million and your damages are $3 million, you may need to sue the broker to recover the difference. An attorney can evaluate the insurance policies and determine if the broker's contingent coverage or negligent hiring liability can be tapped. You can get connected with a lawyer who specializes in these complex insurance disputes.
The Role of Federal Trucking Regulations in Liability
Federal regulations from the Federal Motor Carrier Safety Administration (FMCSA) set the minimum safety standards for commercial trucks. While these rules primarily target carriers and drivers, they also apply to brokers in specific ways. For instance, 49 CFR 371.7 requires brokers to keep records of each transaction, including the carrier's safety rating and insurance certificate. If a broker fails to maintain these records or hires a carrier without verifying insurance, it is a regulatory violation that can be used as evidence of negligence.
Additionally, the FMCSA's rules on coercion (49 CFR 390.6) prohibit brokers from coercing drivers to violate safety rules. If a broker threatens to withhold payment or blacklist a driver unless they drive while ill or fatigued, the broker is violating federal law. Proving coercion can be difficult, but it is a powerful liability theory. It moves the case from a simple negligence claim to a claim involving willful regulatory violations, which can support punitive damages in some states.
Another key regulation involves the broker's authority. Operating as a broker without proper registration is illegal. If the broker in your case was operating illegally or was a "fly-by-night" operation, they may have no insurance at all. In such cases, identifying the shipper or the carrier's insurance becomes even more critical. Attorneys use the FMCSA's Safety Measurement System (SMS) to check the carrier's history. If the broker used a carrier with a high crash rate, they may be liable for failing to adhere to the standard of care required by the industry.
Preserving Electronic and Shipping Records Early
The most critical step after a truck accident is to preserve evidence. In the digital age, this means more than just taking photos at the scene. The broker and carrier hold a vast amount of electronic data that can prove who was at fault. This includes GPS tracking data, electronic logging device (ELD) files, dispatch messages, and load tenders. Without a formal preservation letter, these records may be overwritten or destroyed under normal data retention policies.
Here is a checklist of records that must be preserved immediately:
- ELD data and hours-of-service logs: To prove driver fatigue or hours violations.
- Dispatch and broker communications: Emails, texts, and call logs between the broker and the driver or carrier.
- Driver qualification files: Including drug test results, driving history, and medical certifications.
- Maintenance records: To check for mechanical failures that the carrier or broker knew about.
- Broker-carrier contract and insurance certificates: To establish the legal relationship and coverage limits.
If you are unsure how to draft a spoliation letter or where to send it, you should seek professional help. The longer you wait, the higher the risk that the broker's IT department deletes the very emails that show they pressured the driver. An attorney can send these letters on your behalf, putting the companies on notice that they will face sanctions if evidence is destroyed. This step is often the difference between a successful claim and a dismissed case.
Determining Who Is Liable: A Complex Web
In a truck accident with a broker involved, who is liable for the crash is rarely a simple answer. It requires a deep dive into the contracts, the safety history of the carrier, and the communications leading up to the crash. The broker will almost always deny responsibility, pointing to the driver and the carrier. However, by uncovering evidence of negligent hiring, coercion, or direct control, you can hold the broker accountable. This is not a task for someone recovering from injuries. It requires the resources and legal knowledge of a qualified attorney.
If you are struggling to get answers from insurance companies or are being pressured to accept a low settlement, remember that you have options. You can request a free, no-obligation case review to speak with an attorney who understands the trucking industry. There is no cost to ask questions, and it ensures your rights are protected. Call (855)-545-2917 today to discuss your situation and find out who may be liable for your crash.