Do I Need a Lawyer If the Insurance Company Accepts Fault?
A quick fault admission is not a fair offer. Get a free case review to protect your recovery. Call (855)-545-2917 to speak with our team today.
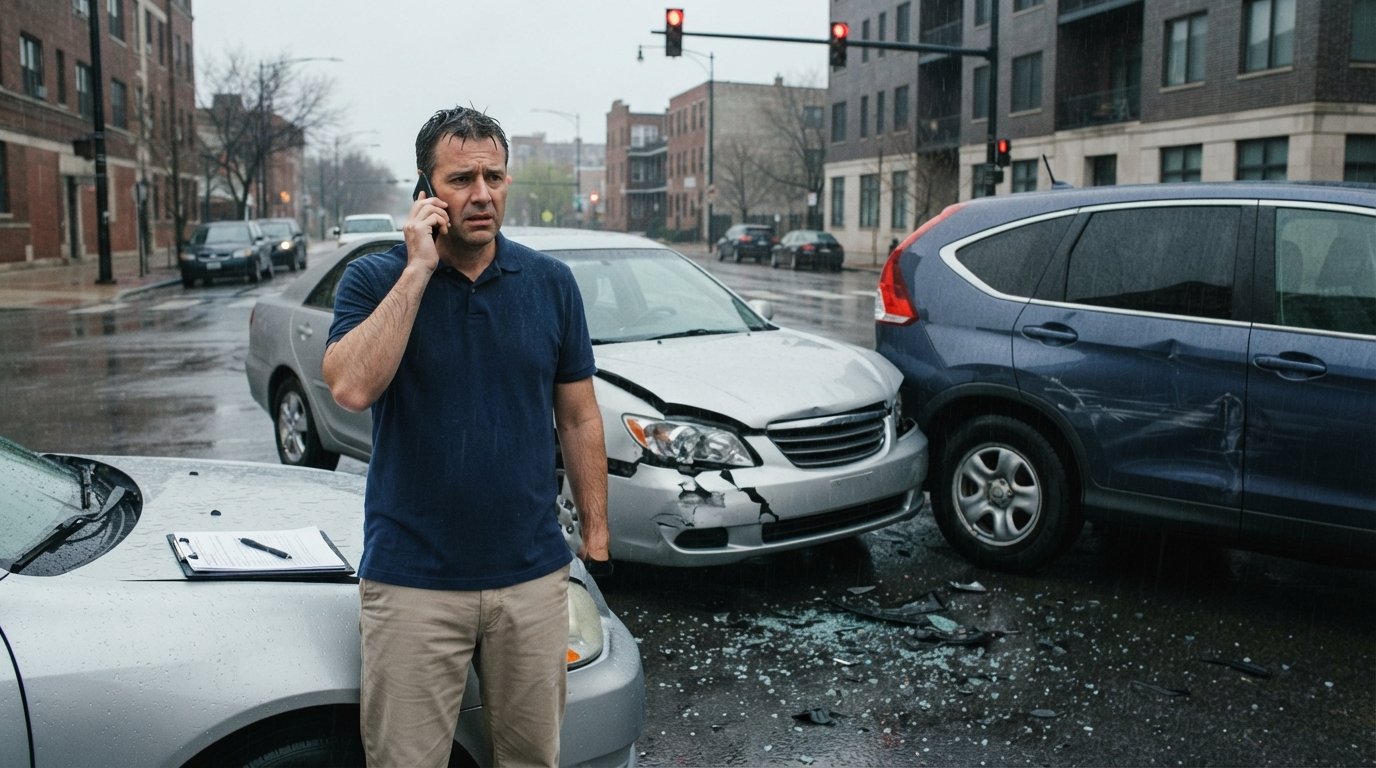
The other driver ran the red light, and their insurance company has already admitted fault. The adjuster sounds friendly, apologetic, and eager to settle. It feels like the hard part is over, so why would you need to call a lawyer? That question, do I need a lawyer if the insurance company accepts fault quickly, is one of the most common and most consequential questions injured people ask. The short answer is that a quick admission of fault is not the same as a fair offer. Liability is only one piece of a personal injury claim, and the settlement number is where most people lose money.
Insurance companies are businesses. An adjuster who accepts fault on day three is often laying the groundwork for a low settlement on day thirty. Understanding how that process works, what to check before you sign anything, and when a free case review makes sense can protect thousands of dollars in medical bills and lost wages. This guide breaks down the realities behind fast fault acceptance and gives you a practical framework for deciding whether to involve an attorney.
Why a Quick Fault Acceptance Does Not Guarantee a Fair Offer
When an insurer accepts fault quickly, it is resolving the question of who caused the crash. It is not resolving the question of what your injuries are worth. Those are two separate calculations, and adjusters know that injured people often conflate them. A fast admission can create psychological momentum: you feel heard, you feel validated, and you feel pressure to cooperate with the nice person on the phone. That momentum is exactly what a low initial offer relies on.
There is also a structural reason insurers move fast on liability. In many crashes, fault is obvious (rear-end collisions, red-light runners, drunk drivers). The insurer saves nothing by denying the obvious, and disputing clear liability can expose the company to bad-faith allegations later. So the adjuster concedes fault, builds rapport, and then controls the narrative on damages. Damages include medical costs, future treatment, lost income, pain and suffering, and other losses. Those numbers are negotiable, and the first offer is almost never the final one.
Consider a typical sequence. You are rear-ended, the other carrier accepts fault within a week, and the adjuster offers $4,000 for soft-tissue injuries before you have finished physical therapy. You feel relieved and sign a release. Six weeks later, an MRI reveals a herniated disc, and you learn the release bars any further claim. The acceptance of fault was real, but the settlement was premature. That gap between liability and damages is where legal guidance earns its keep.
How Adjusters Value Claims and Where Injuries Get Missed
Adjusters use formulas, software, and internal guidelines to price claims. Medical bills and documented lost wages are the foundation. Then they apply multipliers or software-driven ranges for pain and suffering, adjusted for factors like treatment consistency, pre-existing conditions, and the clarity of fault. The process is not designed to be generous; it is designed to be defensible. If a number can be justified internally, it can be offered externally.
Injuries get missed for predictable reasons. Soft-tissue damage, concussions, and spinal injuries often do not show up on an emergency room X-ray. Adrenaline can mask symptoms for days. Many people delay treatment because they feel loyal to their jobs or assume the pain will fade. Adjusters know this, and they often push early settlement before the medical picture is complete. Once you sign, the claim is closed regardless of what the MRI shows later.
The recorded statement is another pressure point. Adjusters frequently ask for a recorded statement shortly after accepting fault, framing it as routine. In our guide on insurance company recorded statement requests, we explain how casual answers about your health, your activities, or the severity of the crash can be used to discount your claim later. You are not required to give a recorded statement to the other driver's insurer, and agreeing to one without preparation rarely helps you.
Here is where a structured review helps even when fault is clear:
- Complete medical documentation: An attorney can wait until treatment is finished or a prognosis is clear, rather than settling on an incomplete record.
- Accurate wage loss: Self-employed workers, gig drivers, and people with irregular schedules often underdocument lost income.
- Future costs: Ongoing therapy, surgery, and lost earning capacity are frequently omitted from early offers.
- Liens and subrogation: Health insurers and hospitals may have reimbursement claims that reduce your net recovery if they are not negotiated.
None of these issues require a courtroom. Most resolve through documentation and negotiation, but they require someone who knows what an adjuster is looking for and what the claim is actually worth.
What to Review Before Signing a Release
A release is a contract. When you sign it, you give up the right to pursue any further claim related to the crash, including claims you do not yet know about. That is why the timing of a settlement matters as much as the amount. Before signing anything, walk through a short checklist with a skeptical eye.
- Is your treatment finished or is a prognosis documented? If you are still treating, or if a specialist has not weighed in, the full value of your claim is unknown.
- Does the offer cover all economic losses? Add up every medical bill, every co-pay, every mile driven to appointments, and every hour of missed work, including overtime and bonuses.
- Are liens addressed? Confirm in writing how health insurance, Medicaid, Medicare, or hospital liens will be resolved so you are not surprised by a bill after the settlement check clears.
- Does the release name all parties? A release that names only the driver may leave the vehicle owner or another responsible party out, or it may accidentally release them.
- Is the language broader than the crash? Some releases include language that waives unknown injuries. Read the fine print, not just the dollar figure.
If any item on that list is unclear, that is a signal to pause. You can ask the adjuster questions, and you can decline to sign until you understand the document. An insurer that has already accepted fault has little incentive to withdraw the admission, but it has every incentive to close the file quickly and cheaply.
When a Case Review Makes Sense Even With Clear Liability
A case review is not a commitment to sue. It is a confidential assessment of whether your claim is being valued fairly and whether an attorney can add value. Several situations make that review especially worthwhile, even when fault is not in dispute.
First, significant or ongoing injuries. If you have fractures, disc injuries, traumatic brain injury symptoms, or a treatment plan that extends weeks or months into the future, the claim is likely worth more than an early offer reflects. Second, disputed damages. If the adjuster accepts fault but disputes the severity of your injuries or claims a pre-existing condition caused your symptoms, an attorney can gather the records and expert input needed to push back. Third, low policy limits. If the at-fault driver carries minimum coverage and your damages exceed it, an attorney can examine uninsured or underinsured motorist coverage on your own policy, which many people overlook.
Fourth, liability spread across multiple parties. Multi-vehicle crashes, rideshare accidents, and trucking cases often involve several insurers and complex fault allocation, even when one company accepts responsibility early. Fifth, pressure to sign quickly. If an adjuster is pushing a deadline that feels artificial, that urgency usually benefits the insurer, not you.
For people who want a no-pressure starting point, services like CheapInjuryLawyer.com offer a free, confidential case review and connect injured people with participating personal injury attorneys, many of whom work on contingency. That model matters because it removes the upfront cost concern that keeps many people from asking questions at all. A review does not create an attorney-client relationship and does not obligate you to hire anyone; it simply gives you information before you make a decision.
It is also worth understanding the contingency fee structure. Most personal injury attorneys are paid a percentage of the recovery, and many offer free initial consultations. That means the practical question is not usually whether you can afford a lawyer, but whether the expected increase in your recovery exceeds the fee. For small claims that resolve quickly with full documentation, handling it yourself can be reasonable. For claims involving ongoing treatment, disputed injuries, or coverage complications, the math often favors at least a consultation.
The No-Obligation Nature of a Confidential Case Review
Many injured people hesitate to call an attorney because they fear being pushed into a lawsuit or a long-term contract. A properly run case review does neither. The purpose is to evaluate the facts, review the offer, and explain your options in plain language. You can ask questions, compare the offer to what the claim may be worth, and then decide. If you choose not to hire the attorney, nothing happens. No fee is owed for the review, and no obligation attaches.
Confidentiality is equally important. What you share in a case review is protected, and it does not become public or get reported to the at-fault insurer. This matters because many people worry that talking to a lawyer will somehow complicate a claim that is already moving along. In practice, a review often clarifies the situation: sometimes it confirms that the offer is fair, and sometimes it reveals gaps that are worth addressing before you sign.
It also helps to know what a review is not. It is not legal advice until an attorney-client relationship is formed. It is not a guarantee of a higher settlement. It is not a requirement to file suit. It is a structured conversation about your claim, your documents, and your choices. For a decision this consequential, that conversation is usually worth having, even if you ultimately decide to proceed on your own.
Practical Steps After a Fast Fault Acceptance
If the other insurer has accepted fault, you are in a stronger position than many claimants, but the work is not done. Start by documenting everything: photos of the vehicles and scene, witness names, the police report, all medical records, bills, and pay stubs. Keep a simple journal of symptoms, appointments, and how the injuries affect daily life. This record is the backbone of any claim, whether you handle it yourself or hire counsel.
Next, avoid recorded statements and informal chats with the other insurer until you understand your injuries. You can be polite and responsive without giving a statement. Ask for offers in writing, and compare them against your documented losses. If the numbers do not add up, or if treatment is ongoing, seek a second opinion before signing. Deadlines vary by state, and fault rules and insurance requirements differ across the country, so confirm the specifics that apply where you live rather than relying on general rules of thumb.
Finally, remember that accepting fault is a starting point, not a finish line. The adjuster's job is to close the claim for as little as possible, and your job is to make sure the number reflects the full impact of the crash. Whether you use an attorney or not, that mindset protects you. If you want a confidential, no-cost review of your situation, a case review can tell you where you stand before you sign away your rights.